The 2026 Missouri Foreclosure Risk Index
Where financial pressure on Missouri homeowners is building, county by county
 Published on October 14th, 2026, by John Carter | Founder, NestCash
Original NestCash research, free to read and cite.
Abstract
Missouri still has a below-average foreclosure rate, but over the past two years it has risen faster than in any neighboring state. In the first half of 2026, 2,749 Missouri properties had a foreclosure filing, one for every 1,028 housing units, the 33rd-highest rate of any state and below the national rate of one in 632. But that was 32 percent more than in the first half of 2025 and 59 percent more than in the first half of 2024, against national increases of 21 and 28 percent. That two-year increase is larger than in any of Missouri’s eight neighbors, the next highest being Arkansas at 55 percent (ATTOM Data Solutions). At the end of 2025, 0.9 percent of Missouri mortgages were 90 or more days delinquent, the same as the national rate and up from 0.6 percent two years earlier, matching the national trend (Consumer Financial Protection Bureau).
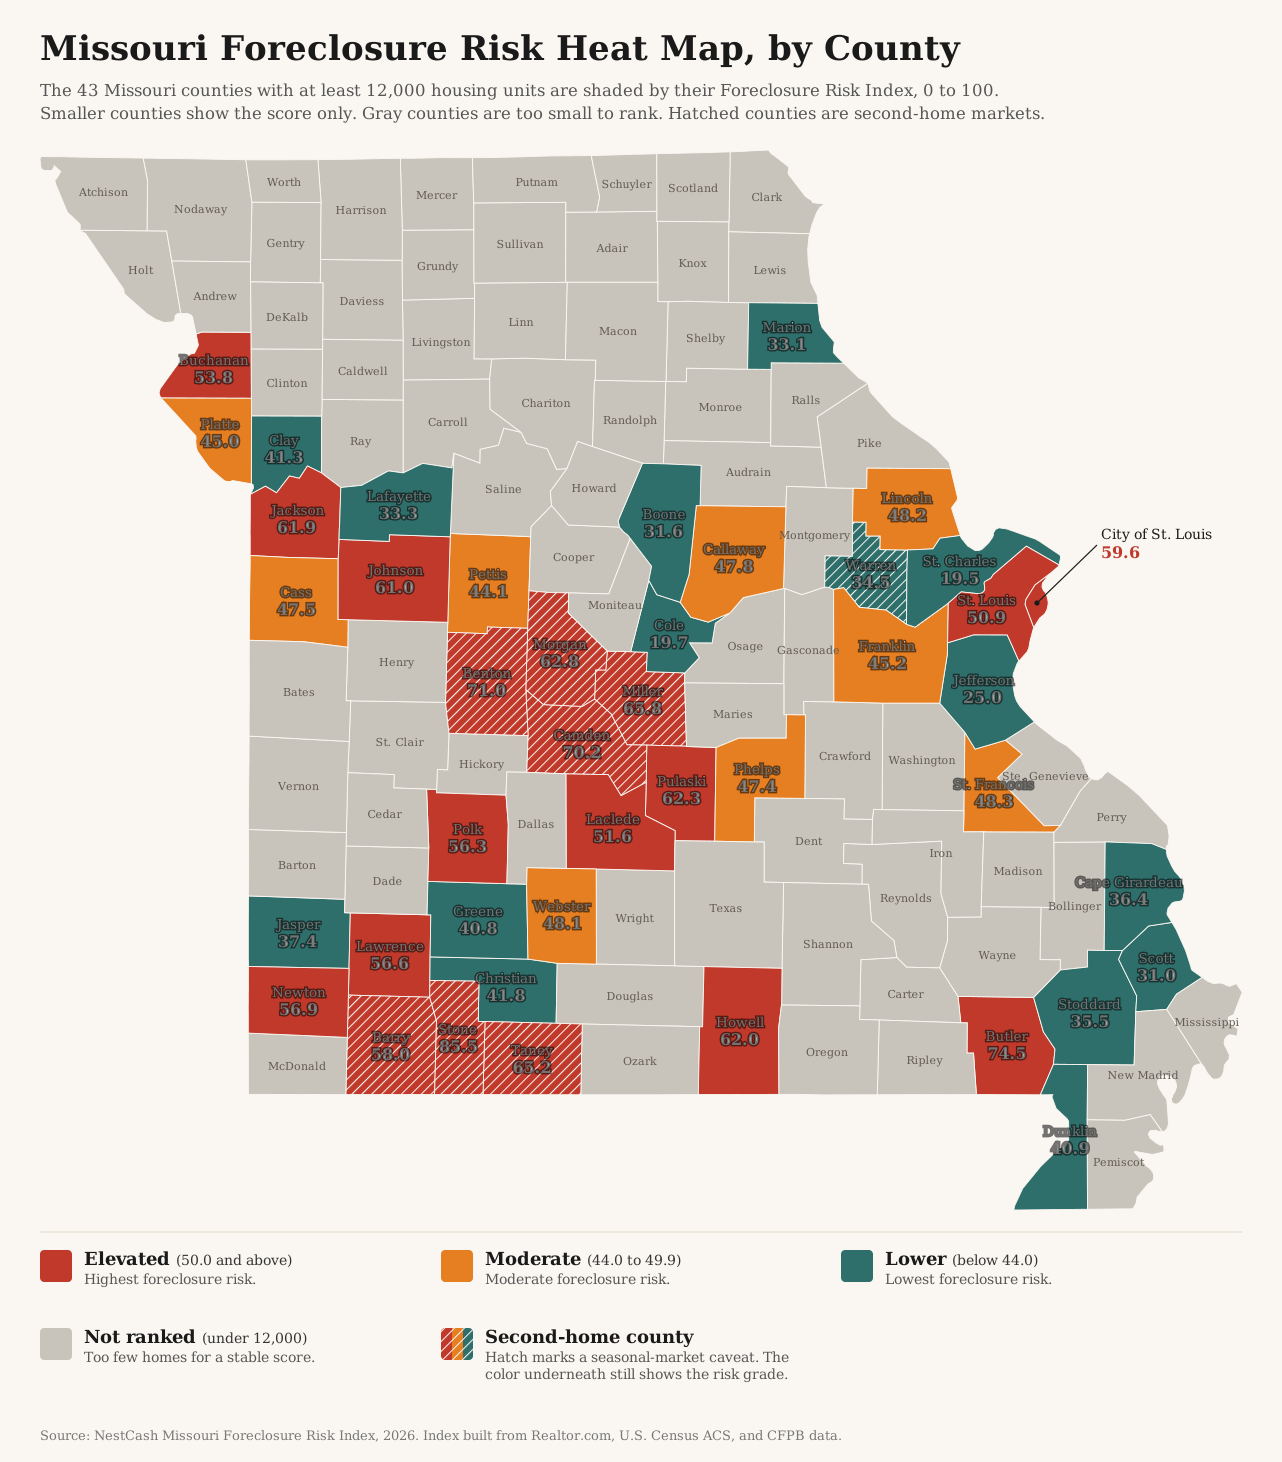
We built a county-level Foreclosure Risk Index from four public datasets to see where the pressure is building. It shows up in three places. The first is the lake and resort country of the Ozarks, where Stone, Benton, Camden, Miller, Taney, and Morgan counties rank among the top seven. These are second-home markets, and we flag them throughout the report. The second is the southern part of the state outside the lake country, led by Butler County, home to Poplar Bluff, which ranks second and is the highest-ranked county that is not a second-home market. The third is the state’s two big cities: Jackson County, home to most of Kansas City, and the City of St. Louis both grade Elevated in every version of the index we tested. The suburbs score lowest. St. Charles County, west of St. Louis, is last in the state at 19.5.
We score each county from 0 to 100 by blending four public signals, each weighted by how directly it bears on a mortgaged homeowner: market softness (35 percent), mortgage cost burden (30 percent), 90-day mortgage delinquency (20 percent), and unemployment (15 percent). Each signal is min-max normalized within Missouri, so the score ranks counties against one another in the state, not against a national or absolute standard. A county grades Elevated at 50 or above, Moderate from 44 to 49.9, and Lower below 44. One rule keeps the ranking honest: we rank the 43 counties with at least 12,000 housing units. Missouri has 114 counties plus the independent City of St. Louis, which we treat as a county. The other 72 have too few homes for sale to score a market reliably, so they stay in the data but are not ranked. The 43 ranked counties hold 84.8 percent of the state’s homes. Because several of the top-ranked counties are second-home markets, we flag them, and we tested the index five different ways and report which findings hold in all of them. The full weighting, the normalization, and the limits of the data are spelled out in the methodology section below.
Key findings
- Missouri’s filings are low but rising fast. It ranked 33rd by foreclosure rate in the first half of 2026, but first-half filings were up 59 percent from two years earlier, a larger increase than in any of its eight neighbors (ATTOM Data Solutions). Its serious delinquency rate rose from 0.6 percent at the end of 2023 to 0.9 percent at the end of 2025.
- The Ozarks lake country leads the index. Stone County ranks first at 85.5, is first in four of the five versions of the index, and grades Elevated in all five. Benton, Camden, Miller, Taney, and Morgan also rank in the top seven and grade Elevated in every version. All six are second-home markets, where 11 to 52 percent of homes are held for seasonal use.
- Poplar Bluff is the highest-ranked year-round county. Butler County ranks second at 74.5, first when market softness is measured by price cuts alone combined with current unemployment, and Elevated in every version. Its owners carry the heaviest housing cost burden of any ranked county, 32.6 percent.
- Jackson County (Kansas City) and the City of St. Louis grade Elevated. Jackson County (61.9) and the City of St. Louis (59.6) are Elevated in all five versions, and in the third quarter of 2026 ATTOM listed both, along with St. Louis County and Greene County, under Missouri in its report on zombie foreclosures. Jackson County has the highest published delinquency rate in Missouri, 1.0 percent.
- The St. Louis suburbs and the capital score lowest. St. Charles County is last at 19.5, with Cole County, home to Jefferson City, at 19.7 and Jefferson County at 25.0. All three grade Lower in every version.
Methodology
Three limits to read first
We state these before the method because they shape how the Missouri results should be read.
Second-home counties near the top. Median days on market is half of the market-softness input, and in second-home markets it is likely inflated by vacation homes that sit longer on the market. Statewide, 2.9 percent of Missouri’s homes are held for seasonal, recreational, or occasional use, and the 5 percent cutoff we have used in several states would flag 36 of Missouri’s 115 counties. As in our Alabama, Utah, and Wisconsin indexes, we instead flag counties at three times the statewide share, 8.6 percent. Eight ranked counties clear that line: Camden (52.3 percent), Morgan (37.5), Benton (31.9), Stone (29.3), Taney (18.7), Miller (11.0), Barry (10.5), and Warren (9.0). St. Francois County, at 5.0 percent, is the next ranked county below the line. Seven of the 19 Elevated counties are on the list. Six of them stay Elevated in every version of the index, so their scores do not rest on days on market alone. Barry County is the exception: it falls to Moderate when market softness is measured by price cuts alone.
Delinquency data for eight of 43 ranked counties. The CFPB publishes a county’s 90-day delinquency rate only when the county has enough mortgages in its sample. In Missouri, eight ranked counties qualify: St. Louis County, Jackson, the City of St. Louis, St. Charles, Greene, Clay, Jefferson, and Boone. The other 35, including every lake county and Butler, carry the statewide rate of 0.9 percent. Their scores rest on market softness, cost burden, and unemployment, not on a measured delinquency rate.
Most counties are too small to rank. Missouri has 115 county-equivalents, and 72 of them have fewer than 12,000 housing units. All four counties ATTOM listed for Missouri in its August 2026 filing report, Ripley, Mississippi, Dallas, and New Madrid, are among them. Our ranked counties cover 84.8 percent of the state’s homes, but the index cannot speak to the smallest rural counties.
We kept the standard formula anyway. Changing the method state by state would break the comparability that makes the series useful, and disclosing where the result is fragile is more useful to readers than tuning it away.
Data and sources
We built the index entirely from public and openly licensed data, and we cite each source at the point of use. Market conditions come from Realtor.com Economic Research (county listing data through September 2026). Housing tenure, mortgage status, cost burden, seasonal homes, county housing counts, and unemployment come from the U.S. Census Bureau’s American Community Survey five-year estimates (2020 to 2024). Mortgage delinquency comes from the Consumer Financial Protection Bureau’s Mortgage Performance Trends (latest data December 2025). Current county unemployment for the sensitivity test comes from the Bureau of Labor Statistics’ Local Area Unemployment Statistics. Statewide filing counts, national ranks, and trends come from ATTOM Data Solutions’ published foreclosure market reports. Every dataset we used is free and publicly available.
Building the index
The Missouri Foreclosure Risk Index uses the same formula as every state in this series, a weighted blend of four signals, each chosen because it precedes or predicts foreclosure among homeowners who carry a mortgage:
35%
The share of active listings with a price cut and the median days a home sits on the market. A soft market matters because a homeowner in trouble who cannot sell quickly has fewer ways to avoid foreclosure. See the note on second-home counties above.
30%
The share of owners with a mortgage who spend 30 percent or more of household income on housing. This is direct payment stress on the exact population that can be foreclosed on.
20%
The 90-day-or-more delinquency rate, the clearest early warning that foreclosures are coming. Published for eight of Missouri’s 43 ranked counties. See the note above.
15%
A secondary driver. We hold its weight down deliberately, because unemployment also captures renters and therefore dilutes a signal meant to describe homeowners.
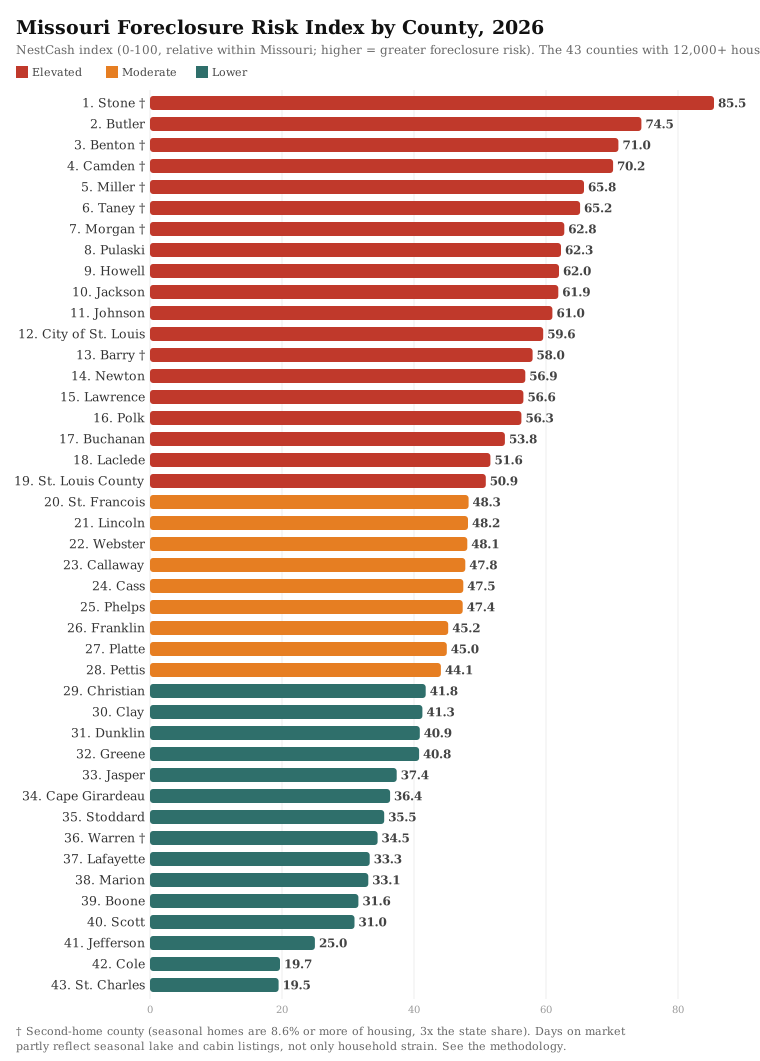
We normalized each signal across the 43 ranked counties on a 0-to-1 scale, where 0 is the lowest value in that set and 1 is the highest, then applied the weights above and multiplied by 100. The result is a relative score: it ranks Missouri counties against one another, not against a national or absolute standard. We then graded each county by its score, Elevated for 50.0 or above, Moderate for 44.0 to 49.9, and Lower for anything below 44.0. Nineteen counties land in the Elevated tier, nine in Moderate, and 15 in Lower. The 19 Elevated counties hold 45.8 percent of the state’s homes, because St. Louis County, Jackson County, and the City of St. Louis are among them.
To test how much the results depend on any one input, we scored the counties five ways: the standard index; the standard index with current Bureau of Labor Statistics unemployment, the 12 published months from August 2025 through August 2026, in place of the Census five-year estimate; the index with delinquency removed and its weight spread proportionally across the other three signals; the index with market softness measured by price cuts alone; and price cuts alone combined with current BLS unemployment. When we call a finding robust in this report, it holds in all five.
Other limitations
The index is relative. A Lower grade means lower measured risk than other Missouri counties, not low risk in absolute terms. It also measures leading pressure, not completed foreclosures or filings, so it will not match any single month’s filing counts. Counties that tie at the published one-decimal score share a rank.
Findings
The index
Ranked from most to least risk on the standard formula. Read the daggered second-home counties with the limits above in mind.
The Ozarks lake country
Six of the seven highest scores of any ranked Missouri county belong to the lake and resort counties of the Ozarks, the region around the Lake of the Ozarks, Truman Lake, Table Rock Lake, and Branson. Stone County scores 85.5, 11.0 points ahead of second place, and ranks first in four of the five versions of the index. Benton (71.0), Camden (70.2), Miller (65.8), Taney (65.2), and Morgan (62.8) follow, and all six grade Elevated in every version.
These counties carry real pressure on year-round homeowners. Morgan (32.1 percent) and Camden (31.6 percent) have the second- and third-heaviest housing cost burdens of any ranked county, and Stone’s five-year unemployment estimate, 7.1 percent, is the highest of any ranked county, though its current 12-month rate is lower, at 5.3 percent. Listings in Taney County have been on the market a median of 98 days and in Stone County 95, the longest of any ranked counties. But these are also the most seasonal housing markets in the state, where 11 to 52 percent of homes are held for seasonal use, and none of them has a published delinquency rate. Taney shows how much the seasonal market can move a rank: it falls from sixth to 19th when market softness is measured by price cuts alone, though it stays Elevated.
Poplar Bluff and southern Missouri
Butler County, home to Poplar Bluff, ranks second at 74.5. It is the highest-ranked county that is not a second-home market, with 2.0 percent of its homes held for seasonal use, and it ranks first or second in all five versions of the index. Its owners carry the heaviest housing cost burden of any ranked county, 32.6 percent, and 23.0 percent of its listings carry a price cut. Howell County (62.0), home to West Plains, Lawrence (56.6), and Polk (56.3) also grade Elevated in every version, and Newton (56.9) and Laclede (51.6) in most. Pulaski County (62.3), home to Fort Leonard Wood, grades Elevated in all five versions. Military moves can lift price cuts and days on market in a base county independent of homeowner strain, so its score should be read with that in mind.
Kansas City and St. Louis
Jackson County, home to most of Kansas City, and the City of St. Louis both grade Elevated. Jackson County scores 61.9 and has the highest published delinquency rate in the state, 1.0 percent. The City of St. Louis, which is independent of any county, scores 59.6, with 25.5 percent of its listings carrying a price cut, the second-highest share of any ranked county. Both grade Elevated in all five versions of the index and rank higher when market softness is measured by price cuts alone. In the third quarter of 2026, ATTOM’s Missouri entry on zombie foreclosures, homes left vacant during the foreclosure process, listed the City of St. Louis, St. Louis County, Jackson, and Greene. On our Vacant & Abandoned Property Index, the City of St. Louis grades Elevated and ranks 83rd of 1,129 U.S. counties, and Missouri ranks 11th of the 50 states and the District of Columbia.
St. Louis County, the largest county in the state with 446,192 homes, grades Elevated at 50.9, but less firmly: it falls to Moderate with current unemployment and to Lower when delinquency is removed. Across the Mississippi in Illinois, St. Clair County, at the center of the Metro-East, grades Elevated in our Illinois Foreclosure Risk Index. On the Kansas City side, Clay (41.3) grades Lower and Platte (45.0) and Cass (47.5) grade Moderate.
The suburbs and Columbia
The lowest scores of any ranked Missouri county belong to suburban and government-center counties. St. Charles County, west of St. Louis, is last at 19.5 on the standard index, with the lowest published delinquency rate in the state, 0.5 percent, a rate it shares with Boone County. Cole County, home to Jefferson City, is at 19.7 and ranks last in the other four versions of the index. Jefferson County, south of St. Louis, scores 25.0. Boone County, home to Columbia, grades Lower at 31.6, and Greene County, home to Springfield, grades Lower at 40.8. All of St. Charles, Cole, Jefferson, and Boone grade Lower in every version.
How today compares with the last crisis
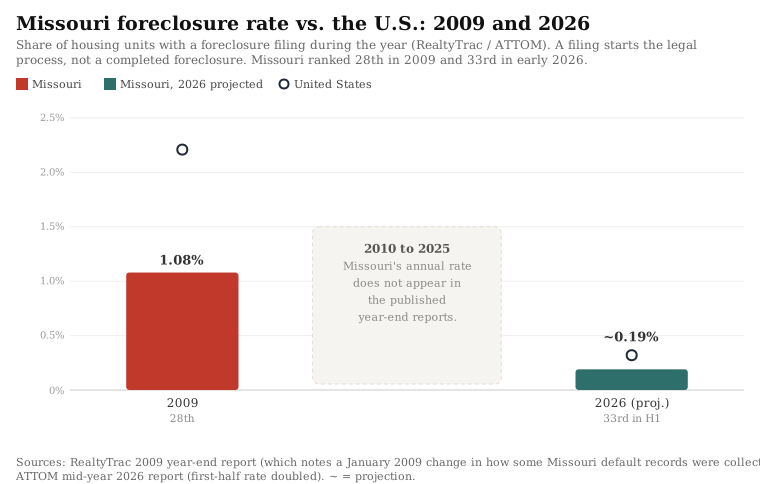
Missouri was a mid-table state in the foreclosure crisis. In 2009, 28,519 Missouri properties received a foreclosure filing, 1.08 percent of the state’s housing against 2.21 percent nationally, which ranked Missouri 28th among the states (RealtyTrac). RealtyTrac noted that it stopped collecting some Missouri default records in January 2009, so its 2009 figure is not directly comparable with earlier years. The published year-end reports we use do not give Missouri’s annual rate for 2010 through 2025, so we cannot say whether 2009 was the state’s peak, and the chart below shows that gap rather than estimating it. Those reports do show Missouri moving against the national trend after the crisis: its foreclosure activity rose 50 percent in 2015, when the nation’s fell, and St. Louis had one of the highest foreclosure rates of any large metro area in 2021 (RealtyTrac and ATTOM). At its first-half pace, Missouri is on track for a 2026 foreclosure rate of roughly 0.19 percent of homes, under a fifth of its 2009 rate and below the national pace of about 0.32 percent.
If you are a Missouri homeowner facing foreclosure
This report is a market analysis, not legal advice, but the data points to a few things worth knowing. In Missouri, a deed of trust can be foreclosed outside of court through a trustee’s sale or by filing suit, at the lender’s option (RSMo 443.410, 443.190). The timeline can be short. The sale must be held in the county where the property is located, with at least 20 days’ notice (RSMo 443.310). Notice is published in a newspaper (443.320) and mailed by certified or registered mail at least 20 days before the sale, and the law does not require that you actually receive it (443.325).
Missouri’s right to redeem a home after the sale is narrow. It applies only when the lender, or someone buying for the lender, buys the home at the sale. You must give written notice of your intent to redeem at the sale or within 10 days before the advertised sale date, give a bond with at least one surety to the satisfaction of the circuit court within 20 days after the sale, and then, within one year, pay the debt and interest plus any taxes, prior liens, and sale costs the buyer paid (RSMo 443.410, 443.420). If anyone else buys the home at the sale, the right does not apply. St. Louis County adopted a foreclosure mediation program in 2012, and the Missouri Supreme Court struck it down in 2014 (Missouri Bankers Ass’n v. St. Louis County).
Help is available. A HUD-approved housing counselor can review your options. Call (800) 569-4287 to find one near you (HUD), or use the CFPB’s housing counselor search. Missouri has four civil legal aid programs, each serving its own set of counties, and the Missouri Legal Services site shows which one serves yours: Legal Services of Eastern Missouri in St. Louis (314-534-4200), Legal Aid of Western Missouri in Kansas City (816-474-6750), Mid-Missouri Legal Services in Columbia (573-442-0116), and Legal Services of Southern Missouri in Springfield (417-881-0533). St. Louis County residents are served by Legal Services of Eastern Missouri. The Missouri Division of Finance takes complaints about state-regulated mortgage lenders and brokers at (573) 751-3242 (Division of Finance). The state’s SAFHR for Homeowners program, which used federal Homeowner Assistance Fund money, is no longer accepting applications (SAFHR for Homeowners). Be wary of anyone who charges up-front fees to stop a foreclosure or asks you to sign over the deed to your home.
The full data
All 43 ranked counties, from highest to lowest Foreclosure Risk Index. An asterisk on the delinquency rate marks a county where the Missouri statewide rate was substituted because its own rate is not separately reported. A dagger marks a second-home county, where seasonal homes are 8.6 percent or more of housing. Unemployment is the five-year Census estimate used in the index. Counties that tie at the published score share a rank.
| Rank | County | FRI | Grade | Price cuts | Median DOM | Cost burden | 90+ delinq | Unemployment |
|---|---|---|---|---|---|---|---|---|
| 1 | Stone † | 85.5 | Elevated | 22.3% | 95 | 29.6% | 0.9*% | 7.1% |
| 2 | Butler | 74.5 | Elevated | 23.0% | 61 | 32.6% | 0.9*% | 4.8% |
| 3 | Benton † | 71.0 | Elevated | 25.2% | 71 | 29.0% | 0.9*% | 3.8% |
| 4 | Camden † | 70.2 | Elevated | 18.5% | 77 | 31.6% | 0.9*% | 4.3% |
| 5 | Miller † | 65.8 | Elevated | 18.8% | 73 | 27.5% | 0.9*% | 5.3% |
| 6 | Taney † | 65.2 | Elevated | 17.9% | 98 | 26.2% | 0.9*% | 3.9% |
| 7 | Morgan † | 62.8 | Elevated | 18.8% | 62 | 32.1% | 0.9*% | 2.9% |
| 8 | Pulaski | 62.3 | Elevated | 23.5% | 52 | 26.6% | 0.9*% | 4.7% |
| 9 | Howell | 62.0 | Elevated | 20.1% | 74 | 24.6% | 0.9*% | 5.0% |
| 10 | Jackson | 61.9 | Elevated | 23.2% | 51 | 24.3% | 1.0% | 4.7% |
| 11 | Johnson | 61.0 | Elevated | 26.1% | 48 | 24.5% | 0.9*% | 4.7% |
| 12 | City of St. Louis | 59.6 | Elevated | 25.5% | 52 | 22.9% | 0.9% | 5.0% |
| 13 | Barry † | 58.0 | Elevated | 16.1% | 83 | 24.4% | 0.9*% | 4.6% |
| 14 | Newton | 56.9 | Elevated | 20.8% | 52 | 23.1% | 0.9*% | 5.9% |
| 15 | Lawrence | 56.6 | Elevated | 21.1% | 72 | 22.3% | 0.9*% | 4.3% |
| 16 | Polk | 56.3 | Elevated | 22.8% | 58 | 23.8% | 0.9*% | 4.0% |
| 17 | Buchanan | 53.8 | Elevated | 23.8% | 47 | 23.0% | 0.9*% | 4.2% |
| 18 | Laclede | 51.6 | Elevated | 16.7% | 59 | 22.9% | 0.9*% | 5.3% |
| 19 | St. Louis County | 50.9 | Elevated | 21.5% | 50 | 22.3% | 0.9% | 4.3% |
| 20 | St. Francois | 48.3 | Moderate | 23.7% | 47 | 19.2% | 0.9*% | 4.5% |
| 21 | Lincoln | 48.2 | Moderate | 24.8% | 59 | 17.8% | 0.9*% | 3.7% |
| 22 | Webster | 48.1 | Moderate | 18.4% | 62 | 21.8% | 0.9*% | 3.8% |
| 23 | Callaway | 47.8 | Moderate | 17.1% | 66 | 19.5% | 0.9*% | 5.1% |
| 24 | Cass | 47.5 | Moderate | 20.6% | 50 | 21.1% | 0.9*% | 4.2% |
| 25 | Phelps | 47.4 | Moderate | 19.6% | 68 | 19.3% | 0.9*% | 3.9% |
| 26 | Franklin | 45.2 | Moderate | 16.9% | 63 | 20.1% | 0.9*% | 4.3% |
| 27 | Platte | 45.0 | Moderate | 21.0% | 57 | 20.9% | 0.9*% | 2.7% |
| 28 | Pettis | 44.1 | Moderate | 17.2% | 46 | 23.0% | 0.9*% | 3.8% |
| 29 | Christian | 41.8 | Lower | 21.8% | 48 | 18.6% | 0.9*% | 3.4% |
| 30 | Clay | 41.3 | Lower | 21.4% | 46 | 20.6% | 0.8% | 3.8% |
| 31 | Dunklin | 40.9 | Lower | 13.0% | 64 | 19.3% | 0.9*% | 4.8% |
| 32 | Greene | 40.8 | Lower | 19.4% | 50 | 21.9% | 0.8% | 3.4% |
| 33 | Jasper | 37.4 | Lower | 19.5% | 47 | 17.5% | 0.9*% | 3.6% |
| 34 | Cape Girardeau | 36.4 | Lower | 19.0% | 48 | 19.5% | 0.9*% | 2.3% |
| 35 | Stoddard | 35.5 | Lower | 13.2% | 59 | 18.8% | 0.9*% | 3.7% |
| 36 | Warren † | 34.5 | Lower | 12.2% | 53 | 20.0% | 0.9*% | 3.7% |
| 37 | Lafayette | 33.3 | Lower | 19.2% | 58 | 14.5% | 0.9*% | 3.0% |
| 38 | Marion | 33.1 | Lower | 15.3% | 46 | 17.8% | 0.9*% | 3.8% |
| 39 | Boone | 31.6 | Lower | 24.0% | 52 | 19.0% | 0.5% | 3.8% |
| 40 | Scott | 31.0 | Lower | 14.6% | 54 | 17.4% | 0.9*% | 2.9% |
| 41 | Jefferson | 25.0 | Lower | 16.1% | 46 | 20.7% | 0.6% | 3.2% |
| 42 | Cole | 19.7 | Lower | 12.0% | 36 | 15.6% | 0.9*% | 2.9% |
| 43 | St. Charles | 19.5 | Lower | 18.5% | 44 | 18.9% | 0.5% | 2.9% |
Seventy-two counties are not ranked because they fall below the 12,000-housing-unit floor: Adair, Andrew, Atchison, Audrain, Barton, Bates, Bollinger, Caldwell, Carroll, Carter, Cedar, Chariton, Clark, Clinton, Cooper, Crawford, Dade, Dallas, Daviess, DeKalb, Dent, Douglas, Gasconade, Gentry, Grundy, Harrison, Henry, Hickory, Holt, Howard, Iron, Knox, Lewis, Linn, Livingston, Macon, Madison, Maries, McDonald, Mercer, Mississippi, Moniteau, Monroe, Montgomery, New Madrid, Nodaway, Oregon, Osage, Ozark, Pemiscot, Perry, Pike, Putnam, Ralls, Randolph, Ray, Reynolds, Ripley, Saline, Schuyler, Scotland, Shannon, Shelby, St. Clair, Ste. Genevieve, Sullivan, Texas, Vernon, Washington, Wayne, Worth, and Wright.
What we will watch
We plan to update this index quarterly, beginning with the first quarter of 2027. Three things will tell us where Missouri goes from here: whether the statewide delinquency rate, which rose from 0.6 percent to 0.9 percent over two years, keeps climbing; whether filings keep rising faster than in neighboring states; and whether Jackson County and the City of St. Louis, the two urban counties that grade Elevated in every version and have measured delinquency, move further up or back toward the middle. ATTOM’s August 2026 report listed the Kansas City metro area, which extends into Kansas, among the five large metros with the biggest year-over-year drop in foreclosure starts, so the next quarter will show whether that relief reaches Jackson County.
Sources and data
- Foreclosure activity and trend. ATTOM Data Solutions, 2026 Mid-Year U.S. Foreclosure Market Report, U.S. Foreclosure Rates by State, August 2026 (published September 18, 2026), and Zombie Foreclosure Rates by State, Q3 2026 (published September 4, 2026). Used for statewide filing counts, national ranks, the one-year and two-year changes, and the counties listed for August filings and third-quarter zombie foreclosures.
- Historical record. RealtyTrac, 2009 Year-End Foreclosure Market Report (via the Financial Crisis Inquiry Commission archive), and the RealtyTrac and ATTOM year-end reports for 2015 and 2021. Used for Missouri’s 2009 rate and rank and its post-crisis trend.
- Housing market softness. Realtor.com Economic Research, county inventory core metrics through September 2026.
- Housing, mortgage status, cost burden, seasonal homes, and unemployment. U.S. Census Bureau, American Community Survey five-year estimates, 2020 to 2024.
- Current unemployment. U.S. Bureau of Labor Statistics, Local Area Unemployment Statistics, the 12 published months from August 2025 through August 2026 (BLS published no October 2025 figures). Used only for the sensitivity test.
- Mortgage delinquency. CFPB Mortgage Performance Trends, state and county data through December 2025. Used for the 90-or-more day delinquency rates and the national and state comparisons.
- Foreclosure process. Revised Statutes of Missouri sections 443.190, 443.310, 443.320, 443.325, 443.410, and 443.420, and Missouri Bankers Ass’n v. St. Louis County (2014). Help resources from HUD, Missouri Legal Services, the Division of Finance, and SAFHR for Homeowners.
About NestCash
NestCash buys houses for cash in twelve states and publishes original housing and distressed-property research across U.S. markets. Our original housing research helps homeowners, buyers, and investors understand local market conditions. This report may be cited and its charts embedded with attribution to NestCash.
John is the Founder of NestCash and a leading voice in real estate investing and housing market strategy. With experience across 12 states, he helps buyers, sellers, and investors make smarter decisions using real-world insight and market data.