Stop Foreclosure In Philadelphia: Get Your Offer in 24 Hours
Facing foreclosure in Philadelphia? Learn the PA timeline, your legal rights, and how a cash sale can stop foreclosure in Philadelphia before auction day.

Head of Sales, NestCash··9 min read
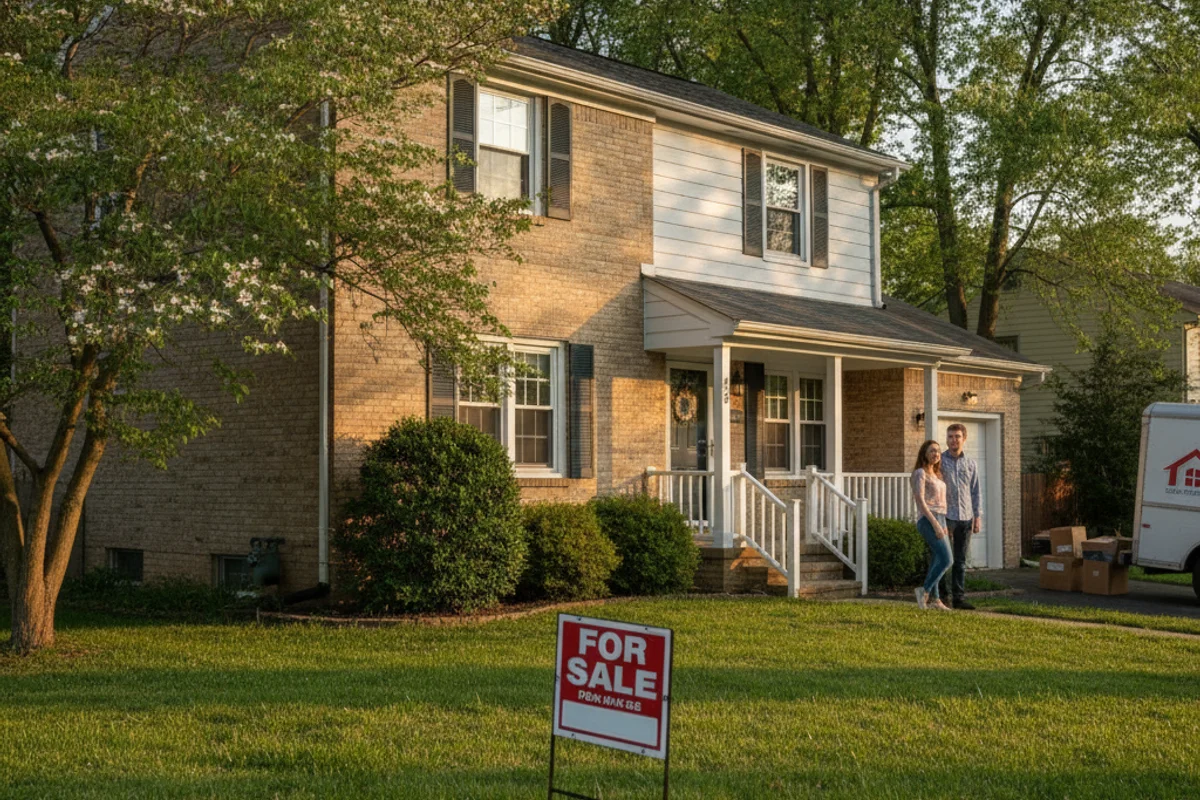
Pennsylvania’s judicial foreclosure timeline moves fast once it starts. From your first missed payment to a scheduled sheriff’s sale, the entire process can unfold in as little as six months. If you’re two or three months behind right now, you may have a narrower window than you think to stop foreclosure in Philadelphia before it permanently damages your financial future. The good news is that you have real options, and one of the most powerful is a cash home sale that can close in days, not months.
This isn’t a failure. It’s a financial decision. Thousands of Philadelphia homeowners in neighborhoods like Kensington, West Philly, and Frankford have used a fast cash sale to walk away with dignity, protect their credit, and move forward on their own terms. Let’s break down exactly what you’re facing and what you can do about it.
The Pennsylvania Foreclosure Timeline: Day by Day
Pennsylvania is a judicial foreclosure state, which means your lender has to go through the court system to take your home. That’s actually good news because it gives you more time and more touchpoints to act.
Here’s how the process typically unfolds:
- Days 1 to 90 (Missed Payments). You miss one or more mortgage payments. Your lender will send notices and attempt contact. No legal action has been filed yet. This is your most flexible window.
- Day 90 to 120 (Notice of Default / Act 91 Notice). Under Pennsylvania’s Homeowner Assistance and Foreclosure Prevention Act (Act 91 of 1983), your lender must send you a formal notice before filing. This notice gives you 33 days to request a meeting with a housing counselor.
- Day 120 to 150 (Complaint Filed in Court). If you don’t resolve the default, your lender files a foreclosure complaint in the Philadelphia Court of Common Pleas. You’ll be formally served.
- Day 150 to 180 (Response Period). You have 20 days to respond to the complaint. Failing to respond can result in a default judgment against you.
- Month 4 to 9 (Judgment and Scheduling). If the court rules in the lender’s favor, a judgment is entered and a sheriff’s sale date is scheduled.
- Sheriff’s Sale Day. Your property is auctioned publicly. Once the sale is confirmed by the court, you lose the home.
- Post-Sale. Unlike some states, Pennsylvania does not provide a statutory right of redemption for most residential mortgages after the sheriff’s sale is confirmed. Your options after this point are extremely limited.
The full timeline can stretch 12 to 18 months if contested, but it can also move in as little as six months. Don’t count on delays to save you.
For a complete guide, read our resource on foreclosure alternatives in Philadelphia.
Get Your Free Cash Offer Today
No fees. No repairs. Close in as little as 7 days.
Related Video
Your Rights as a Philadelphia Homeowner Facing Foreclosure
You have more legal protections than you might realize, but they only work if you use them. Pennsylvania law gives you specific rights throughout this process.
The Act 91 notice requirement means your lender cannot skip straight to court. They have to give you a chance to pursue assistance first. That 33-day window is a real opportunity to contact a HUD-approved housing counselor at no cost. These counselors are certified, free to use, and can help you understand loan modification options, repayment plans, and other alternatives your lender is legally required to consider.
You also have the right to cure the default before a judgment is entered. That means if you can bring the loan current, including missed payments, fees, and legal costs, the foreclosure stops. A cash sale can accomplish the same result if the proceeds cover what you owe.
Pennsylvania also requires standard property disclosures under the Seller Disclosure Law, even in distress situations. A cash buyer familiar with the Pennsylvania market will handle this efficiently and without making it feel like an obstacle.
One thing to be clear about: this article is not legal advice. Every foreclosure situation is different. Consult a licensed Pennsylvania real estate attorney to understand your specific rights and deadlines.
How Selling for Cash Stops the Pennsylvania Foreclosure Process
Here’s the thing about a traditional home sale in Philadelphia. The median home price sits around $280,000 right now, and the average property spends about 61 days on the market before going under contract. Add another 30 to 45 days for the standard Pennsylvania closing process, and you’re looking at 3 to 4 months minimum from listing to settlement.
If you have a sheriff’s sale scheduled in 45 days, a traditional listing won’t save you.
That’s where Philadelphia cash home buyers change the equation entirely. A reputable cash buyer can:
- Make an offer within 24 hours of seeing your home
- Skip the inspection contingency, appraisal, and mortgage approval delays
- Close in 7 to 14 days, or on whatever timeline you need
- Buy your home as-is, meaning no repairs, no cleaning, no staging costs
When the sale closes, the proceeds first pay off your mortgage balance, any arrears, and associated legal fees. If there’s equity remaining, that money is yours. And critically, the foreclosure process stops because the debt is satisfied. The lender has no reason to continue.
This is why roughly 25% of Philadelphia home sales are already cash transactions. Cash buyers are not a niche. They’re a legitimate and growing part of the local real estate market, especially in neighborhoods where homes may need updating or where sellers need speed above all else.
For a side-by-side look at what you’d actually net in each scenario, check out our breakdown in Cash Offer Vs Listing With Realtor In Philadelphia: Real Numbers.
Find Out What Your Home Is Worth
Get a no-obligation cash offer in 24 hours.
What Foreclosure Does to Your Credit Score
Let’s be direct about this because it matters more than most people realize.
A completed foreclosure typically drops your credit score by 100 to 150 points. If you’re starting with a score of 680, you could land in the low 500s, which affects your ability to rent an apartment, get a car loan, or qualify for a new mortgage for years. According to CFPB housing guidance, a foreclosure stays on your credit report for seven years.
That’s seven years of higher interest rates, security deposit requirements, and financial stress following you around.
Here’s the contrast: selling your home before the auction, even at a discount from the full market value, typically results in a far smaller credit impact. Missed payments will still affect your score, but a resolved mortgage with no foreclosure judgment is a fundamentally different mark on your report than a completed sheriff’s sale.
Protecting your credit isn’t vanity. It’s a practical financial decision that will affect where you live and how much you pay for everything after this chapter closes.
Philadelphia Foreclosure Alternatives You May Not Know About
A cash sale is one path, but it’s worth knowing all the tools available to you before making any decisions.
Loan Modification. Your lender may agree to change the terms of your mortgage, lowering the interest rate or extending the loan term to reduce your monthly payment. This keeps you in the home. Contact your lender’s loss mitigation department directly or through a HUD counselor.
Forbearance Agreement. Some lenders will temporarily pause or reduce your payments if you’re facing a short-term hardship. This buys time without adding to the legal timeline.
Short Sale. If you owe more than your home is worth, a short sale lets you sell the property for less than the outstanding mortgage balance with lender approval. It still affects your credit, but less severely than a foreclosure.
Deed in Lieu of Foreclosure. You voluntarily transfer ownership of the home to the lender in exchange for being released from the mortgage debt. It avoids the public auction process.
Bankruptcy (Chapter 13). Filing for Chapter 13 bankruptcy triggers an automatic stay, which immediately halts foreclosure proceedings. This can give you time to reorganize your finances, but it’s a serious legal step that requires an attorney.
Each of these has tradeoffs. What works for a homeowner in Brewerytown might not be the right fit for someone in Northeast Philly. Take the time to understand your specific numbers before committing to any path.
If you’re considering what a cash offer would actually look like compared to listing with an agent, our neighbors in other Pennsylvania cities have faced the same choice. See how Pittsburgh homeowners have avoided foreclosure with a cash sale as a reference point for what the process looks like.
How to Sell Your Philadelphia Home Before the Auction Date
Time is the most important resource you have right now. Here’s a practical, step-by-step approach to moving fast.
Step 1: Know your exact auction date. Check the Philadelphia Sheriff’s Office sale schedule and confirm any court filings through the Philadelphia Court of Common Pleas. You need the hard deadline before you can plan around it.
Step 2: Get a cash offer immediately. Contact Philadelphia cash home buyers and request a same-day or next-day offer. Reputable buyers will assess your home quickly, often with a brief walkthrough or even based on photos and public records for an initial number.
Step 3: Review what you owe. Call your lender and get a payoff statement. This tells you the exact amount needed to satisfy the mortgage. Compare that to the cash offer to understand if there will be remaining equity, or if a short sale conversation with your lender is needed.
Step 4: Consult a Pennsylvania attorney. Even a brief consultation can clarify whether the foreclosure timeline has any remaining procedural steps that could give you additional time, or confirm that you need to close before a specific date.
Step 5: Accept the offer and set a closing date. Work with the cash buyer to set a closing date that beats the auction. Most cash buyers in Philadelphia can accommodate a 7 to 10 day closing with flexibility built in.
Step 6: Close and move forward. At settlement, the mortgage is paid off, the foreclosure process ends, and any remaining proceeds come to you. You leave the table with your credit protected and a clean break.
When you’re ready to take that first step, you can get your cash offer within 24 hours. There’s no obligation, no pressure, and no cost to find out what your home is worth to a cash buyer today.
We buy houses in Pennsylvania with homeowners across the state, and we understand that Philadelphia’s market, its neighborhoods, its court system, and its homeowners have unique needs. We also work with homeowners in Allentown, Pittsburgh, and Reading who face similar situations. But right now, if you’re in Philly and you’re reading this, the most important thing is that you act before the clock runs out.
You have options. You have rights. And you have time, but only if you use it now.
We also help homeowners in Philadelphia dealing with divorce, selling as-is, and inherited property situations.
Ready to Sell? Let's Talk.
Get your cash offer now. No obligation, no hassle.
Jessica is the Head of Sales at NestCash and a real estate professional known for her market expertise and customer-first approach. Working across 12 states, she helps shape strategies that support buyers, sellers, and investors with confidence.