The 2026 Nevada Foreclosure Risk Index
Where financial pressure on Nevada homeowners is building, county by county
 Published on September 28th, 2026, by John Carter | Founder, NestCash
Original NestCash research, free to read and cite.
Abstract
Nevada led the country in foreclosure rate for five straight years during the last housing crisis, and it is near the top of the table again. In the first half of 2026 the state recorded 2,935 foreclosure filings, one for every 452 housing units, the sixth-highest rate in the nation. In July it had the worst monthly rate of any state, and in August the second worst (ATTOM Data Solutions).
The statewide number describes a state that is really two housing markets. Clark County, home to Las Vegas, holds 71.5 percent of Nevada’s housing, and Washoe County, home to Reno, holds most of the rest. We built a county-level Foreclosure Risk Index from four public datasets to see how evenly the pressure is shared. It is not shared evenly.
Nye County, the desert county that includes Pahrump, tops the index at 93.8. Clark County ranks second at 74.6 and grades Elevated. Washoe County grades Lower at 31.0, and so does Elko County in the northeast. The difference between Nevada’s two big metros is the central finding of this report, and it holds up when we remove the one input we trust least.
This report explains how the index is built, publishes every county score, and states its limits plainly. Nevada’s county-level delinquency data is thin, and we describe exactly how much that matters.
We score each county from 0 to 100 by blending four public signals, each weighted by how directly it bears on a mortgaged homeowner: market softness (35 percent), mortgage cost burden (30 percent), 90-day mortgage delinquency (20 percent), and unemployment (15 percent). Each signal is min-max normalized within Nevada, so the score ranks counties against one another in the state, not against a national or absolute standard. A county grades Elevated at 50 or above, Moderate from 44 to 49.9, and Lower below 44. One rule keeps the ranking honest: we rank the seven counties with at least 12,000 housing units. Nevada has 17 counties, and the other 10 have too few homes for sale to score a market reliably, so they stay in the data but are not ranked. The seven ranked counties hold 97.3 percent of the state’s homes. Because published delinquency rates exist for only two Nevada counties, we also scored the index without delinquency and report which results change. The full weighting, the normalization, and the limits of the data are spelled out in the methodology section below.
Key findings
- Nevada is back near the top of the national foreclosure table. First-half 2026 filings totaled 2,935, one per 452 housing units, the sixth-highest rate in the country and up about 6 percent from the first half of 2025. Nevada then posted the worst state foreclosure rate in July 2026 (one filing per 1,703 housing units) and the second worst in August, behind only South Carolina (ATTOM Data Solutions).
- Las Vegas and Reno are on opposite sides of the index. Clark County grades Elevated at 74.6. Washoe County grades Lower at 31.0. Clark carries a higher mortgage cost burden (32.1 percent against 27.6), higher unemployment (7.6 percent against 5.1), and the largest share of price-cut listings of any ranked county, 24.2 percent.
- Pahrump, not Las Vegas, is the top of the index. Nye County scores 93.8, the highest in the state by 19 points. Its mortgaged owners carry a 39.6 percent housing cost burden and its unemployment rate is 8.1 percent, both the highest of any ranked county and both above Nevada’s statewide figures of 31.2 and 7.0 percent.
- The result does not depend on the delinquency data. County-level delinquency rates exist for only Clark and Washoe. When we drop that input entirely and reweight the other three, Nye and Clark remain first and second, and Washoe remains in the Lower tier.
- Actual filings point to the same counties. ATTOM’s August 2026 state ranking named Lyon, Clark, Nye, and Mineral as the Nevada counties with the worst foreclosure rates that month. The first three are the top three counties in our index. Mineral falls below our 12,000-home ranking floor. Our index measures underlying conditions, not filings, so this agreement is an independent check rather than a restatement of the same data.
- Nevada foreclosures take a long time to finish. Homes whose foreclosures were completed in the second quarter of 2026 had been in the process for an average of 1,507 days, the fifth-longest timeline in the country and nearly three times the national average of 563 days (ATTOM Data Solutions).
Methodology
Data and sources
We built the index entirely from public and openly licensed data, and we cite each source at the point of use. Market conditions come from Realtor.com Economic Research (county listing data through August 2026). Housing tenure, mortgage status, cost burden, county housing counts, and unemployment come from the U.S. Census Bureau’s American Community Survey five-year estimates (2020 to 2024). Mortgage delinquency comes from the Consumer Financial Protection Bureau’s Mortgage Performance Trends (latest data December 2025). Statewide filing counts, national ranks, and trends come from ATTOM Data Solutions’ published foreclosure market reports. Every dataset we used is free and publicly available.
Building the index
The Nevada Foreclosure Risk Index uses the same formula as every state in this series, a weighted blend of four signals, each chosen because it precedes or predicts foreclosure among homeowners who carry a mortgage:
35%
The share of active listings with a price cut and the median days a home sits on the market. A soft market matters because a homeowner in trouble who cannot sell quickly has fewer ways to avoid foreclosure.
30%
The share of owners with a mortgage who spend more than 30 percent of household income on housing. This is direct payment stress on the exact population that can be foreclosed on.
20%
The 90-day-or-more delinquency rate, the clearest early warning that foreclosures are coming. See the note on Nevada’s delinquency data below.
15%
A secondary driver. We hold its weight down deliberately, because unemployment also captures renters and therefore dilutes a signal meant to describe homeowners.
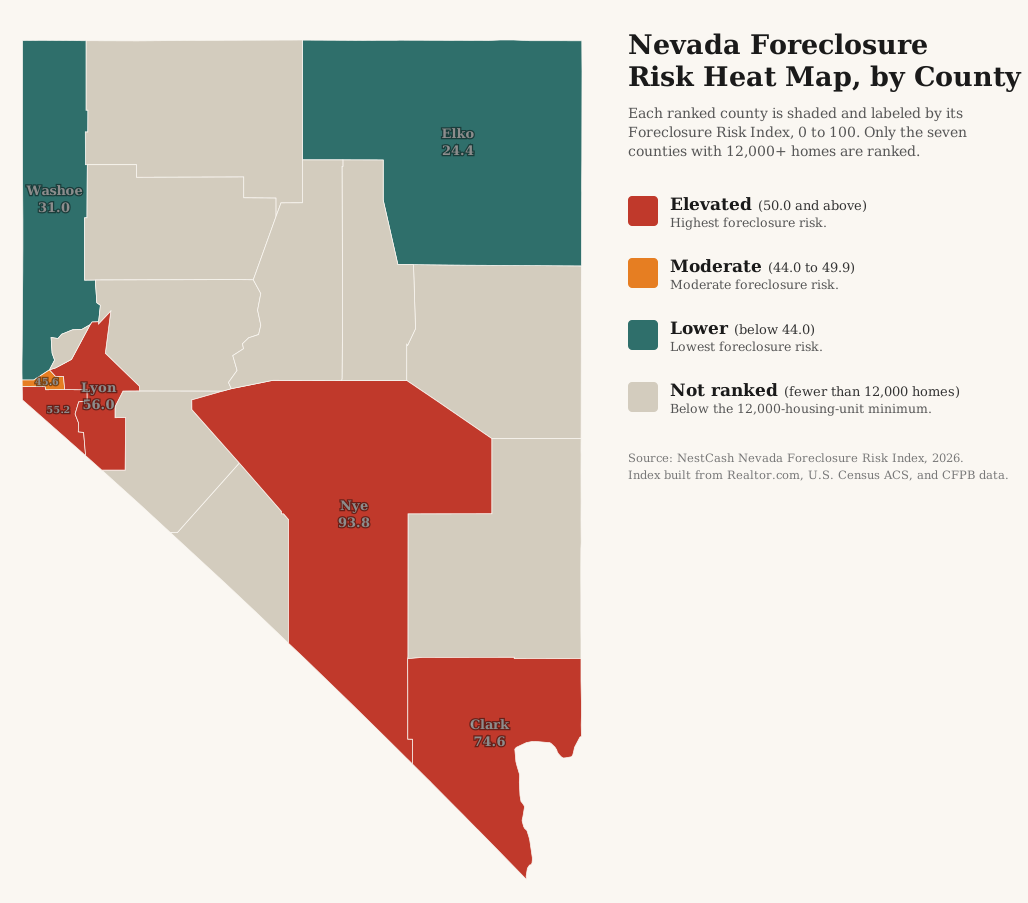
We normalized each signal across the ranking-eligible counties on a 0-to-1 scale, where 0 is the lowest value in that set and 1 is the highest, then applied the weights above and multiplied by 100. The result is a relative score: it ranks Nevada counties against one another, not against a national or absolute standard. We then graded each county by its score, Elevated for 50.0 or above, Moderate for 44.0 to 49.9, and Lower for anything below 44.0. Four counties land in the Elevated tier, one in Moderate, and two in Lower.
Nevada has 17 counties, and most are very small. We limited the ranking to counties with at least 12,000 housing units, the same floor we use across this series, because price-cut shares and days-on-market figures drawn from a handful of listings are too noisy to rank. Two rural Nevada counties had fewer than ten active listings in August 2026, and every other county below the floor had fewer than 50. That leaves seven ranked counties, which together hold 97.3 percent of the state’s housing. The other ten are shown in gray on the map and listed below the table, with no score or rank.
A note on Nevada’s delinquency data
This is the most important limitation in the report, so we state it here rather than at the end.
County-level mortgage delinquency data was available from the CFPB for Clark and Washoe counties only. The CFPB publishes a county’s rate only when the county has at least 1,000 mortgages in its sample, and no other Nevada county qualifies. For the other five ranked counties we used the Nevada statewide rate of 0.8 percent. Because the index rescales each indicator across the ranked counties, small differences in delinquency rates can have an outsized effect on relative scores. In Nevada the full range is 0.6 percent (Washoe) to 0.8 percent (Clark and the statewide rate), so a 0.2-point difference moves a county across the entire 20 percent delinquency weight.
We kept the standard formula so that Nevada remains comparable with the other states in the series, and we tested how much the delinquency input changes the result. With delinquency removed and the other three signals reweighted, Nye County scores 92.3 and Clark County 68.3, and they remain the two highest-ranked counties. Washoe County scores 38.7 and remains Lower. Lyon and Douglas counties are the two results that move: without delinquency they fall from Elevated to the top of the Moderate tier. We treat their Elevated grades as less certain than Nye’s and Clark’s.
Other limitations
First, the index is relative. A Lower grade means lower risk than other Nevada counties, not low risk in absolute terms, and Nevada as a whole has one of the highest foreclosure rates in the country. Second, with only seven ranked counties, normalization stretches the scale: the highest county scores near 100 and the lowest near the bottom by construction, so gaps between counties look larger than they would in a state with 60 ranked counties. Third, the index measures leading pressure, not completed foreclosures. Where our scores and realized foreclosure counts disagree, we say so rather than force a match.
Findings
The index: two metros, two grades
Ranked from most to least risk, the index splits Nevada along a line that runs between its two largest cities.
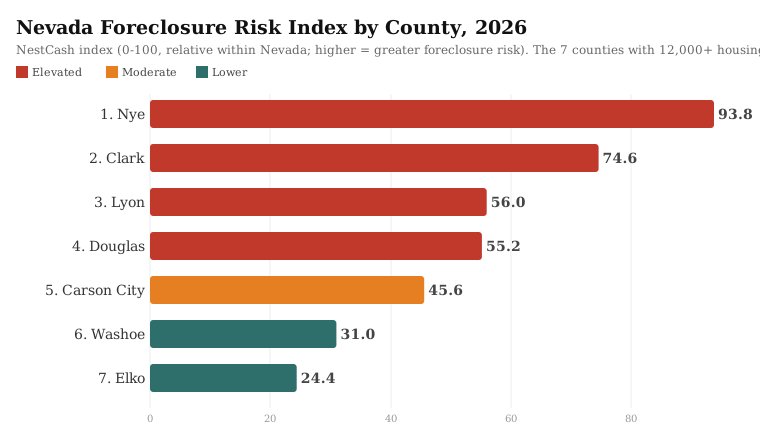
Clark County grades Elevated at 74.6, and because it holds 948,995 housing units, it is the county that determines what Nevada’s statewide numbers look like. It is under pressure on every input. Its 24.2 percent price-cut share is the highest of any ranked county, its mortgaged owners carry a 32.1 percent cost burden, and its unemployment rate is 7.6 percent, second only to Nye. Its 0.8 percent serious delinquency rate is one of only two county rates the CFPB publishes for Nevada, and it is the higher of the two. ATTOM’s metro data points the same way: the Las Vegas metro had the third-worst foreclosure rate of any U.S. metro with at least 200,000 residents in July 2026, one filing for every 1,394 housing units.
Nevada is not alone in this. Across the 13 states in this series, the largest county grades Elevated in seven, including Cook County in our Illinois index and Philadelphia in our Pennsylvania index. What stands out in Nevada is how much of the state that one county is. Because Clark County grades Elevated, more than three-quarters of Nevada’s homes sit in an Elevated county.
Washoe County is the contrast. Reno’s market is not strong on every measure. Its 22.0 percent price-cut share is the second highest among ranked counties. But its owners are less stretched, with a 27.6 percent cost burden, its unemployment rate is 5.1 percent, and its delinquency rate of 0.6 percent is the lowest the CFPB reports anywhere in the state. It scores 31.0. Some of the 44-point gap between Clark and Washoe comes from the delinquency input, which is exactly the effect described in our methodology note. But when we remove delinquency altogether the gap is still 30 points, and Washoe still grades Lower.
Nye County: the top of the index
Nye County, whose largest community is Pahrump, about an hour’s drive west of Las Vegas, scores 93.8. That is 19 points above Clark and the highest score in the state.
It gets there on the two inputs that describe household strain most directly. Nye’s mortgaged owners carry a 39.6 percent housing cost burden, the highest of any ranked county and more than eight points above Nevada’s statewide figure of 31.2 percent. Its unemployment rate of 8.1 percent is also the highest of any ranked county, above the statewide 7.0 percent. Its housing market is soft as well: 19.6 percent of active listings carry a price cut, and the typical home sits 71 days, against a median of 52 days across the ranked counties.
This is the finding the statewide numbers cannot show. Nye County has 25,289 housing units, less than 3 percent of Clark’s, so it barely registers in state or metro foreclosure counts. But for an individual homeowner there, the combination of high housing costs, weak local employment, and a slow market is the most difficult in Nevada. Nye County’s delinquency input is the statewide rate, and its rank does not depend on it: without delinquency it still scores 92.3.
Around Carson City, and the northeast
Lyon County (56.0) and Douglas County (55.2), both south and east of Carson City, grade Elevated, and Carson City itself grades Moderate at 45.6. These three share a regional market with the Reno area and carry similar cost burdens, between 28 and 32 percent.
Douglas County needs a note. It grades Elevated with an unemployment rate of 3.0 percent, the lowest of any ranked county, and it reaches the Elevated tier on a 31.9 percent cost burden and a slow market (67 median days on market). That combination, high cost burden alongside very low unemployment, is a pattern we have flagged in other states. Douglas County includes the Nevada side of Lake Tahoe, where many homes are second homes, and its cost-burden figure may partly reflect households with high housing costs relative to reported income rather than payment stress. We report Douglas County’s score as the formula produces it, but we would not read it as evidence of distress on the scale of Nye or Clark, and it is one of the two counties that drop to Moderate without the delinquency input.
Elko County in the northeast is the lowest-risk county in the index at 24.4. It has the lowest price-cut share of any ranked county at 11.2 percent, homes sell in a median of 39 days, and its unemployment rate is 4.5 percent.
Rate versus volume
Risk per homeowner and total foreclosure volume are different measurements, and Nevada separates them more sharply than most states. Clark County carries both high risk and overwhelming volume. With 71.5 percent of the state’s housing, it will produce the large majority of Nevada’s foreclosure filings in any year.
Nye County is the opposite case: the highest risk per homeowner in the state, in a county too small to move the state totals. For a homeowner weighing their own exposure, the index is the relevant number. For anyone sizing the market, volume is, and in Nevada volume means Las Vegas.
How today compares with the last crisis
Nevada was the center of the 2007 to 2011 foreclosure crisis. It had the highest state foreclosure rate in the country for five consecutive years, from 2007 through 2011, according to RealtyTrac’s year-end reports. Filings peaked in 2009, when 112,097 Nevada properties received a foreclosure filing, one for every 10 housing units over the full year. There were 106,160 in 2010 and 72,844 in 2011, when Las Vegas also had the worst foreclosure rate of any large metro in the country.
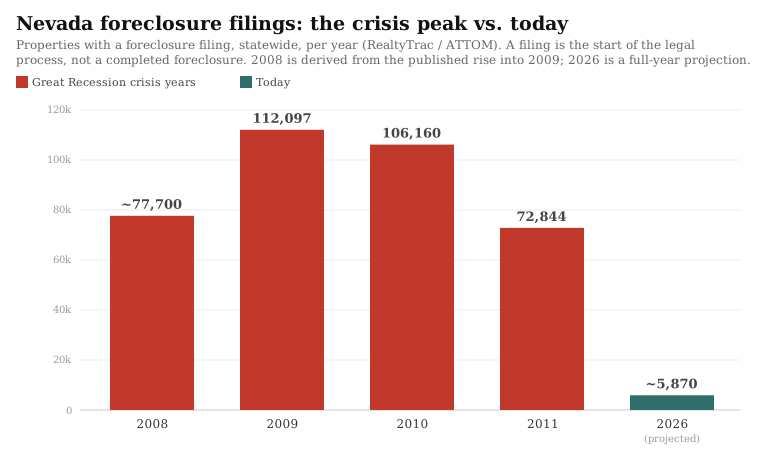
The current numbers are nowhere near that. At the first-half pace of 2,935 filings, Nevada is on track for roughly 5,900 in 2026, about 5 percent of the 2009 peak. What has returned is Nevada’s position in the ranking, not the scale of the problem. Nevada’s filings rose about 6 percent from the first half of 2025, well below the national increase of 21 percent. The state is near the top of the table because its rate has stayed persistently high, not because it is surging.
The long foreclosure timeline is part of the same story. Homes that completed foreclosure in the second quarter of 2026 had been in the process for 1,507 days on average, more than four years (ATTOM Data Solutions). Some of the foreclosures finishing in Nevada today began several years ago, which is worth keeping in mind when reading monthly rankings.
If you are a Nevada homeowner facing foreclosure
This report is a market analysis, not legal advice, but the data points to a few things worth knowing. Most Nevada foreclosures are non-judicial. The process typically begins when the lender’s trustee records a Notice of Default and Election to Sell, and it can proceed to a trustee’s sale without a court case.
Nevada also runs a Foreclosure Mediation Program under rules set by the Nevada Supreme Court. If you receive a Notice of Default on the home you live in, you can petition your district court for mediation, a meeting with a representative of your lender and a state-approved mediator to discuss alternatives to foreclosure. The window is short: the program is available when the Notice of Default was filed within the past 30 days, the property is your primary residence, and you do not have an open bankruptcy case. Filing the petition requires a $25 fee and service on the lender and trustee. The notice is worth opening the day it arrives.
Free help is available. A HUD-approved housing counselor can review your options at no cost, and you can find one through the CFPB’s housing counselor search. In Southern Nevada, the Legal Aid Center of Southern Nevada assists eligible homeowners with foreclosure and foreclosure mediation, and the Civil Law Self-Help Center explains the mediation process step by step. Acting early matters either way, since a foreclosure can stay on a credit report for up to seven years.
The full data
All seven ranked counties, from highest to lowest Foreclosure Risk Index. An asterisk on the delinquency rate marks a county where the Nevada statewide rate was substituted because the county’s own rate is not separately reported. See the methodology note on delinquency data.
Market-softness figures come from Realtor.com’s August 2026 county file. Outside Clark and Washoe, each ranked county had between 117 and 375 active listings, so their price-cut shares and days on market carry more noise than the two metros.
| Rank | County | FRI | Grade | Price cuts | Median DOM | Cost burden | 90+ delinq | Unemployment |
|---|---|---|---|---|---|---|---|---|
| 1 | Nye | 93.8 | Elevated | 19.6% | 71 | 39.6% | 0.8*% | 8.1% |
| 2 | Clark | 74.6 | Elevated | 24.2% | 58 | 32.1% | 0.8% | 7.6% |
| 3 | Lyon | 56.0 | Elevated | 17.5% | 46 | 32.2% | 0.8*% | 6.5% |
| 4 | Douglas | 55.2 | Elevated | 16.5% | 67 | 31.9% | 0.8*% | 3.0% |
| 5 | Carson City | 45.6 | Moderate | 16.6% | 50 | 28.4% | 0.8*% | 5.5% |
| 6 | Washoe | 31.0 | Lower | 22.0% | 52 | 27.6% | 0.6% | 5.1% |
| 7 | Elko | 24.4 | Lower | 11.2% | 39 | 26.2% | 0.8*% | 4.5% |
Ten counties are not ranked because they fall below the 12,000-housing-unit floor: Churchill, Esmeralda, Eureka, Humboldt, Lander, Lincoln, Mineral, Pershing, Storey, and White Pine.
What we will watch
We plan to update this index quarterly, beginning with the first quarter of 2027. Three things will tell us where Nevada goes from here: whether Nevada stays at or near the top of the monthly state rankings, which would suggest persistent rather than temporary pressure; whether Clark County’s 24.2 percent price-cut share keeps rising, since a softening Las Vegas market would reduce homeowners’ options for selling their way out; and whether the CFPB begins publishing delinquency rates for more Nevada counties, which would let us replace the statewide substitute and firm up the Carson Valley results.
Sources and data
- Foreclosure activity and trend. ATTOM Data Solutions, 2026 Mid-Year U.S. Foreclosure Market Report, July 2026 U.S. Foreclosure Market Report, August 2026 U.S. Foreclosure Market Report, and U.S. Foreclosure Rates by State, August 2026 (published September 18, 2026). Used for statewide filing counts, national ranks, the Las Vegas metro rate, foreclosure timelines, the year-over-year change, and the counties with the worst August filing rates.
- Housing market softness. Realtor.com Economic Research, county inventory core metrics through August 2026. Used for the price-cut share, median days on market, and active listing counts.
- Housing, mortgage status, cost burden, and unemployment. U.S. Census Bureau, American Community Survey five-year estimates, 2020 to 2024. Used for county housing counts, the mortgaged-owner universe, housing cost burden, and the unemployment rate.
- Mortgage delinquency. CFPB Mortgage Performance Trends, data through December 2025. Used for the 90-or-more day delinquency rates.
- Historical foreclosure rates. RealtyTrac, 2009 Year-End Foreclosure Market Report (via the Financial Crisis Inquiry Commission archive), and 2010 year-end report, with 2011 coverage from the Las Vegas Sun. Used for Nevada’s national rank from 2007 through 2011 and its 2009, 2010, and 2011 filing counts. The 2008 figure in the history chart is derived from the published 44 percent rise into 2009, and 2026 is a full-year projection from first-half filings.
- Foreclosure mediation. Home Means Nevada, Foreclosure Mediation Program. Used for the mediation eligibility rules and filing requirements.
About NestCash
NestCash buys houses for cash in twelve states and publishes original housing and distressed-property research across U.S. markets. Our original housing research helps homeowners, buyers, and investors understand local market conditions. This report may be cited and its charts embedded with attribution to NestCash.
John is the Founder of NestCash and a leading voice in real estate investing and housing market strategy. With experience across 12 states, he helps buyers, sellers, and investors make smarter decisions using real-world insight and market data.