The 2026 Idaho Foreclosure
Risk Index
Bonner County leads as Idaho foreclosure filings climb
 Published on October 24th, 2026, by John Carter | Founder, NestCash
Original NestCash research, free to read and cite.
Abstract
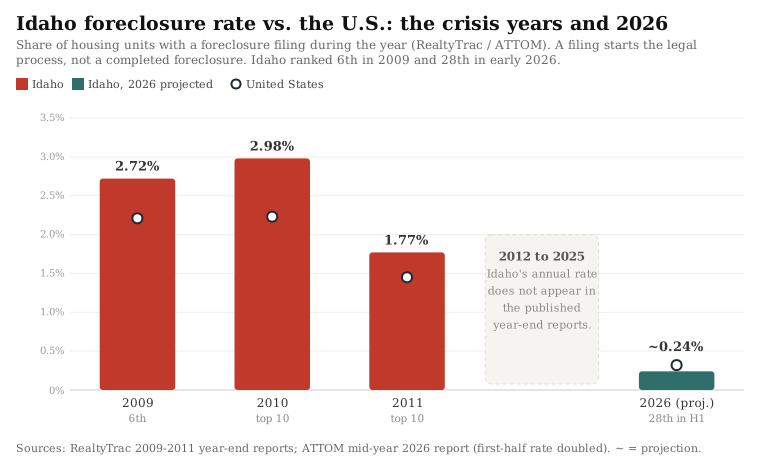
Idaho was one of the states hit hardest by the last foreclosure crisis. In 2009, 2.72 percent of its housing units had a foreclosure filing, the sixth-highest rate of any state, against 2.21 percent nationally (RealtyTrac). Today its rate is below the national one, but its filings are rising faster. In the first half of 2026, 969 Idaho properties had a foreclosure filing, one for every 820 housing units, the 28th-highest rate of any state, against a national rate of one in 632. Filings were 59 percent higher than in the first half of 2025, the largest increase of any state with at least 500 filings, while filings nationally rose 21 percent. Over two years, Idaho’s filings rose 63 percent, against 28 percent nationally (ATTOM Data Solutions). At the end of 2025, 0.6 percent of Idaho mortgages were 90 or more days delinquent, against 0.9 percent nationally (Consumer Financial Protection Bureau).
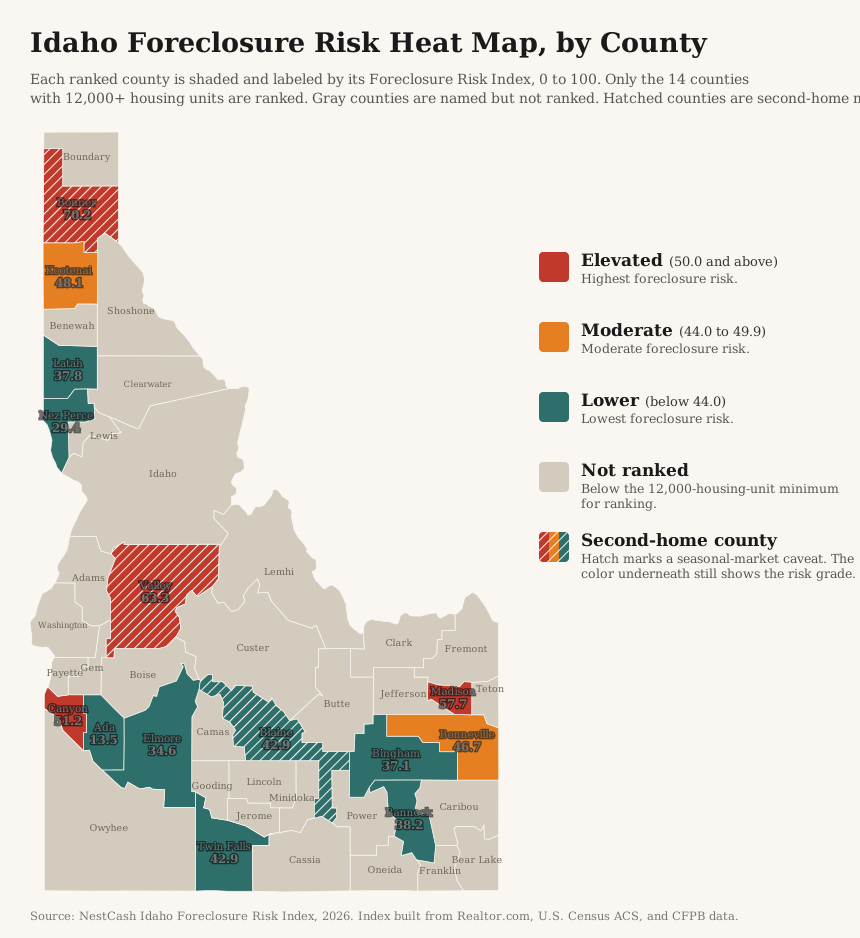
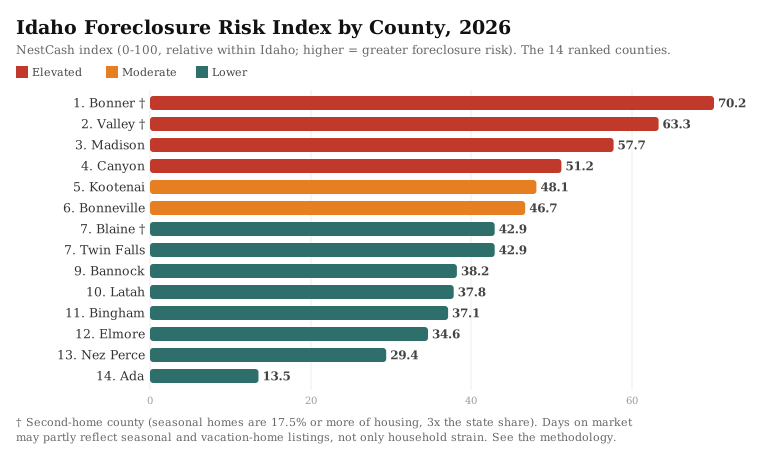
We built a county-level Foreclosure Risk Index from four public datasets to see where the pressure is building. Bonner County, home to Sandpoint and a second-home market we flag throughout the report, ranks first at 70.2, and it ranks first in every version of the index we tested. Valley County, home to McCall and also a second-home market, ranks second at 63.3. Canyon County, home to Nampa and Caldwell, ranks fourth at 51.2 and has the highest published mortgage delinquency rate of any Idaho county. Ada County, home to Boise and Meridian and the state’s largest county by number of homes, ranks last of the 14 ranked counties at 13.5, and it ranks last in every version we tested.
We score each county from 0 to 100 by blending four public signals, each weighted by how directly it bears on a mortgaged homeowner: market softness (35 percent), mortgage cost burden (30 percent), 90-day mortgage delinquency (20 percent), and unemployment (15 percent). Each signal is min-max normalized within Idaho, so the score ranks counties against one another in the state, not against a national or absolute standard. A county grades Elevated at 50 or above, Moderate from 44 to 49.9, and Lower below 44. We rank counties with at least 12,000 housing units, and 14 of Idaho’s 44 counties clear that floor, holding 80.2 percent of the state’s homes. Three ranked counties are second-home markets, and we flag them. We tested the index five different ways and report which findings hold in all of them. The full weighting, the normalization, and the limits of the data are spelled out in the methodology section below.
Key findings
- Idaho’s filings are rising faster than in any other state with at least 500 filings. In the first half of 2026, Idaho’s filings were up 59 percent from a year earlier, ahead of Colorado at 57 percent. Its rate is still below the national rate, the 28th-highest of any state (ATTOM Data Solutions).
- Bonner County ranks first in every version. Bonner scores 70.2 and ranks first in all five versions of the index. Its homeowners with a mortgage carry the second-highest cost burden of any ranked county, its listings sit on the market a median of 86 days, and its current unemployment rate is the highest of any ranked county. It is also a second-home market.
- Canyon and Ada counties sit at opposite ends. Canyon County’s 90-day delinquency rate, 1.0 percent, is the highest published rate of any Idaho county and above the national 0.9 percent. Ada County, next door, has the lowest published rate, 0.3 percent. Canyon ranks fourth and Ada ranks last.
- Only Bonner grades Elevated in every version. Valley, Canyon, and Madison counties grade Elevated on the standard index but drop in at least one other version. Six counties grade Lower in every version: Blaine, Twin Falls, Latah, Elmore, Nez Perce, and Ada.
- The statewide rate is far below the crisis. At its first-half pace, Idaho is on track for about 0.24 percent of its housing units with a filing in 2026, against 2.72 percent in 2009 and 2.98 percent in 2010 (RealtyTrac).
You're on the list.
We'll email you when the next report is out. One optional question so we can send the right research:
Methodology
Three limits to read first
We state these before the method because they shape how the Idaho results should be read.
Delinquency data for 4 of 14 ranked counties. The CFPB publishes a county’s 90-day delinquency rate only when the county has enough mortgages in its sample. In Idaho, four ranked counties qualify: Canyon (1.0 percent), Bonneville (0.8), Kootenai (0.8), and Ada (0.3). The other 10 carry the statewide rate of 0.6 percent, which is lower than three of the four published rates, so it lowers their scores relative to Canyon, Bonneville, and Kootenai. When we remove delinquency from the index, Canyon falls from fourth to eighth and grades Lower, Kootenai and Bonneville also grade Lower, and Blaine and Twin Falls rise to fourth and fifth.
Three second-home counties. Median days on market is half of the market-softness input, and in second-home markets it is likely inflated by vacation homes that sit longer on the market. Statewide, 5.8 percent of Idaho homes are held for seasonal, recreational, or occasional use. Our usual cutoff, 5 percent, would flag 20 of Idaho’s 44 counties, so, as in New York, we flag a county when its share is at least three times the statewide share, 17.5 percent. Three ranked counties clear it: Valley (62.5 percent), Blaine (30.0 percent), home to Hailey and Ketchum, and Bonner (19.2 percent). Kootenai County, at 7.5 percent, is the next ranked county below the line. Bonner grades Elevated in every version of the index, Valley grades Elevated in three versions and Moderate in the two price-cut versions, and Blaine grades Lower in every version.
Unemployment estimates differ. The index uses the Census five-year unemployment estimate, which covers 2020 to 2024 and includes the pandemic shutdowns. In some counties it differs sharply from the current rate from the Bureau of Labor Statistics. In Madison County, home to Rexburg, it runs far above the current rate, 8.3 percent against 3.8 percent, and in Latah County, home to Moscow, 6.8 percent against 3.3 percent. In Kootenai County it runs below it, 3.3 percent against 4.4 percent. With current unemployment, Madison falls from third to fifth and grades Moderate, and we treat its grade as less firm.
We kept the standard formula anyway. Changing the method state by state would break the comparability that makes the series useful, and disclosing where the result is fragile is more useful to readers than tuning it away.
Data and sources
We built the index entirely from public and openly licensed data, and we cite each source at the point of use. Market conditions come from Realtor.com Economic Research (county listing data through September 2026). Housing tenure, mortgage status, cost burden, seasonal homes, county housing counts, and unemployment come from the U.S. Census Bureau’s American Community Survey five-year estimates (2020 to 2024). Mortgage delinquency comes from the Consumer Financial Protection Bureau’s Mortgage Performance Trends (latest data December 2025). Current county unemployment for the sensitivity test comes from the Bureau of Labor Statistics’ Local Area Unemployment Statistics. Statewide filing counts, national ranks, and trends come from ATTOM Data Solutions’ published foreclosure market reports. Every dataset we used is free and publicly available.
Building the index
The Idaho Foreclosure Risk Index uses the same formula as every state in this series, a weighted blend of four signals, each chosen because it precedes or predicts foreclosure among homeowners who carry a mortgage:
35%
The share of active listings with a price cut and the median days a home sits on the market. A soft market matters because a homeowner in trouble who cannot sell quickly has fewer ways to avoid foreclosure. See the note on second-home counties above.
30%
The share of owners with a mortgage who spend 30 percent or more of household income on housing. This is direct payment stress on the exact population that can be foreclosed on.
20%
The 90-day-or-more delinquency rate, the clearest early warning that foreclosures are coming. Published for 4 of the 14 ranked counties. See the note above.
15%
A secondary driver. We hold its weight down deliberately, because unemployment also captures renters and therefore dilutes a signal meant to describe homeowners.
We ranked the 14 counties with at least 12,000 housing units. Smaller counties have few listings in a given month, which makes their market data noisy, and the 14 ranked counties hold 637,768 of Idaho’s 795,014 homes. We normalized each signal across the ranked counties on a 0-to-1 scale, where 0 is the lowest value in that set and 1 is the highest, then applied the weights above and multiplied by 100. The result is a relative score: it ranks Idaho counties against one another, not against a national or absolute standard. We then graded each county by its score, Elevated for 50.0 or above, Moderate for 44.0 to 49.9, and Lower for anything below 44.0. Four counties land in the Elevated tier, two in Moderate, and eight in Lower. The four Elevated counties hold 18.1 percent of the state’s homes.
To test how much the results depend on any one input, we scored the counties five ways. The first is the standard index. The second swaps in current Bureau of Labor Statistics unemployment, the 12 published months from August 2025 through August 2026, for the Census five-year estimate. The third removes delinquency and spreads its weight proportionally across the other three signals. The fourth measures market softness by price cuts alone, and the fifth combines price cuts alone with current BLS unemployment. When we call a finding robust in this report, it holds in all five.
Other limitations
The index is relative. A grade describes a county’s position among Idaho’s ranked counties, not its risk in absolute terms. Ada County’s score of 13.5 means it sits at or near the low end of the ranked counties on most inputs, not that its homeowners face no risk. The index also measures leading pressure, not completed foreclosures or filings, so it will not match any single month’s filing counts. The 30 counties below the housing floor are not ranked, and the index says nothing about them. Counties that tie at the published one-decimal score share a rank, as Blaine and Twin Falls do at 42.9.
Findings
The index
Ranked from most to least risk on the standard formula. Read the daggered second-home counties with the limits above in mind.
Sandpoint, Coeur d’Alene, and the north
Bonner County, home to Sandpoint, scores 70.2 and ranks first in all five versions of the index. Its score does not rest on one input. Of the homeowners there with a mortgage, 39.4 percent spend 30 percent or more of their income on housing, the second-highest share of any ranked county after Valley. Its listings sit on the market a median of 86 days, the third-longest of any ranked county, and its current unemployment rate, 5.2 percent, is the highest of any ranked county. Its delinquency rate is not published. Bonner is also a second-home market, with 19.2 percent of its homes held for seasonal use, so its days on market should be read with that in mind.
Kootenai County, home to Coeur d’Alene and Post Falls, ranks fifth at 48.1 and grades Moderate. Its published delinquency rate is 0.8 percent, and 31.3 percent of its homeowners with a mortgage carry a high cost burden, the fourth-highest share of any ranked county. Kootenai grades Elevated with current unemployment and in both price-cut versions, and Lower when delinquency is removed. In 2025, the call center operator Inspiro reported laying off 100 workers in Coeur d’Alene in a notice to the state (Idaho Statesman). Farther south, Latah County, home to Moscow, ranks 10th and Nez Perce County, home to Lewiston, ranks 13th. Both grade Lower in every version.
Boise, Nampa, and the Treasure Valley
Ada County, home to Boise and Meridian, ranks last at 13.5 and grades Lower in every version. It is the state’s largest county by number of homes, 211,440. Its listings spend less time on the market than in any other ranked county, a median of 44 days, and its published delinquency rate, 0.3 percent, is the lowest of any Idaho county with a published rate. Elmore County, home to Mountain Home, ranks 12th and also grades Lower in every version.
Canyon County, home to Nampa and Caldwell, ranks fourth at 51.2. Its 90-day delinquency rate, 1.0 percent, is the highest published rate of any Idaho county and above the national rate of 0.9 percent. A year earlier it was 0.8 percent. Canyon also has the fourth-highest price-cut share of any ranked county, 21.6 percent of listings. It grades Elevated in four versions of the index and Lower when delinquency is removed, because its published rate drives much of its score. In October 2025, according to the Idaho Statesman, Ada County had 45 properties in foreclosure, about double a year earlier, and Canyon County had 27, up from 19.
Ada and Canyon are a reminder that the index and the zombie count measure different things. In the third quarter of 2026, ATTOM listed Ada, Kootenai, and Canyon counties in its Idaho entry on zombie foreclosures, homes left vacant during the foreclosure process. Idaho had only 12 of them, 2.3 percent of properties in foreclosure, against 3.3 percent nationally. The index describes pressure on mortgaged homeowners across a county. The zombie count describes a handful of homes already in foreclosure.
McCall, Sun Valley, and the resort counties
Valley County, home to McCall and Cascade, ranks second at 63.3. Most of its homes, 62.5 percent, are held for seasonal use, the highest share of any Idaho county. It has the highest cost burden of any ranked county, 39.5 percent, and the longest median time on the market of any ranked county, 95 days. Only 13.2 percent of its listings carry a price cut, so on the two price-cut versions it falls to seventh and fifth and grades Moderate.
Blaine County, home to Hailey, Ketchum, and Bellevue, ties Twin Falls County for seventh at 42.9 and grades Lower in every version. Blaine has the lowest price-cut share of any ranked county, 12.8 percent, and the lowest five-year unemployment estimate of any ranked county, 2.1 percent, but the third-highest cost burden of any ranked county, 34.9 percent. In the region that spans Blaine, Camas, and Lincoln counties, a household earning the median income would have to spend 95 percent of its take-home pay to afford a median home, which falls around $1 million (Idaho Statesman, citing Federal Reserve data).
Idaho Falls, Pocatello, Rexburg, and Twin Falls
Madison County, home to Rexburg, ranks third at 57.7. Its five-year unemployment estimate, 8.3 percent, is the highest of any Idaho county, but its current rate is 3.8 percent, and with current unemployment Madison falls to fifth and grades Moderate. Its listings sit on the market a median of 89 days, the second-longest of any ranked county. Madison grades Elevated in three versions and Lower when price cuts alone are combined with current unemployment.
Bonneville County, home to Idaho Falls and Ammon, ranks sixth at 46.7 and grades Moderate. Its published delinquency rate is 0.8 percent, and 22.7 percent of its listings carry a price cut, the second-highest share of any ranked county. It grades Elevated in both price-cut versions and Lower with current unemployment or with delinquency removed. Bingham County, home to Blackfoot, ranks 11th, and it has the highest price-cut share of any ranked county, 23.4 percent. Bannock County, home to Pocatello and Chubbuck, ranks ninth, and both counties grade Moderate or Elevated on the price-cut versions. Twin Falls County ranks seventh, tied with Blaine at 42.9, and grades Lower in every version. In August 2026, ATTOM listed Caribou, Lincoln, Bannock, and Power counties in its Idaho entry on foreclosure filings. Of those, only Bannock is large enough to be ranked.
How today compares with the last crisis
In 2009, 17,161 Idaho properties had a foreclosure filing, 2.72 percent of the state’s housing units, against 2.21 percent nationally. That rate ranked Idaho sixth (RealtyTrac). In 2010, Idaho’s rate was 2.98 percent, against 2.23 percent nationally, and in 2011 it was 1.77 percent, against 1.45 percent, and both years it was among the 10 highest of any state. In 2011, the Boise metro area ranked 19th among the metro areas RealtyTrac listed, at 2.85 percent. The published year-end reports we use do not give Idaho rates for 2012 through 2025, so the chart shows those years as a gap rather than estimating them. At its first-half pace, Idaho is on track for about 1,938 properties with a filing in 2026, about 0.24 percent of its housing units, against about 0.32 percent nationally. That is about a ninth of the 2009 count, and a rate below the national one, where in the crisis years Idaho’s rate ran above it.
How Idaho compares with its neighbors
In the first half of 2026, Idaho’s foreclosure rate was one in 820 housing units (ATTOM Data Solutions). That was lower than in Nevada, where Nye County ranks first in our county index (one in 452) and Utah, where our county index puts Iron County first (one in 534). It was higher than in Oregon, where Lincoln County leads our county index (one in 1,170) and Washington, where Grays Harbor County ranks first in our county index (one in 1,332).
If you are an Idaho homeowner facing foreclosure
This report is a market analysis, not legal advice, but the data points to a few things worth knowing. A home financed with a deed of trust in Idaho can be sold by a trustee without a court case, after a notice of default is recorded with the county (Idaho Code § 45-1503, § 45-1505). The notice of sale must be mailed at least 120 days before the sale date. Within 115 days of the recording of the notice of default, the homeowner can stop the foreclosure by paying the amount then due, not counting principal that would not be due had there been no default, and the loan is reinstated (§ 45-1506).
If the loan is from a state or federally regulated lender and secures your primary residence (a home with a homeowner’s property tax exemption for that year), the lender must send a notice with a form you can use to request a loan modification and a meeting to discuss your options. If you return the form by the date on the notice, 30 days after the notice is dated, the lender must answer in writing within 45 days, and the trustee’s sale cannot happen until it does (§ 45-1506C). After a trustee’s sale there is no right to redeem the home (§ 45-1508), and the buyer is entitled to possession on the tenth day after the sale (§ 45-1506). A lender that wants a judgment for any remaining balance must seek it within three months, and it is limited to the amount by which the debt exceeds the home’s fair market value (§ 45-1512). A lender can instead foreclose in court (§ 6-101). After a court-ordered sale, the owner can redeem within six months for a tract of 20 acres or less, or within one year for a larger tract (§ 11-402).
Help is available. A HUD-approved housing counselor can review your options: call (800) 569-4287 to find one near you (HUD). Idaho Legal Aid Services takes phone requests for free legal help at 208-746-7541, Monday through Wednesday, 10:00 a.m. to 1:30 p.m. Mountain Time (Idaho Legal Aid Services). The Attorney General’s Consumer Protection Division is at 208-334-2424, or toll-free at 1-800-432-3545 (Idaho Attorney General). If your loan is serviced by the Idaho Housing and Finance Association, call 800-526-7145 (Idaho Housing).
The full data
The 14 ranked counties, from highest to lowest Foreclosure Risk Index. An asterisk on the delinquency rate marks a county where the Idaho statewide rate was substituted because its own rate is not separately reported. A dagger marks a second-home county, where seasonal homes are at least three times the statewide share of housing, 17.5 percent. Unemployment is the five-year Census estimate used in the index. Counties that tie at the published score share a rank.
| Rank | County | FRI | Grade | Price cuts | Median DOM | Cost burden | 90+ delinq | Unemployment |
|---|---|---|---|---|---|---|---|---|
| 1 | Bonner † | 70.2 | Elevated | 19.4% | 86 | 39.4% | 0.6*% | 4.8% |
| 2 | Valley † | 63.3 | Elevated | 13.2% | 95 | 39.5% | 0.6*% | 4.8% |
| 3 | Madison | 57.7 | Elevated | 19.6% | 89 | 26.5% | 0.6*% | 8.3% |
| 4 | Canyon | 51.2 | Elevated | 21.6% | 51 | 28.2% | 1.0% | 3.7% |
| 5 | Kootenai | 48.1 | Moderate | 19.5% | 56 | 31.3% | 0.8% | 3.3% |
| 6 | Bonneville | 46.7 | Moderate | 22.7% | 51 | 26.6% | 0.8% | 4.6% |
| 7 | Blaine † | 42.9 | Lower | 12.8% | 80 | 34.9% | 0.6*% | 2.1% |
| 7 | Twin Falls | 42.9 | Lower | 18.7% | 75 | 29.0% | 0.6*% | 3.0% |
| 9 | Bannock | 38.2 | Lower | 21.9% | 70 | 22.4% | 0.6*% | 4.3% |
| 10 | Latah | 37.8 | Lower | 18.6% | 63 | 23.2% | 0.6*% | 6.8% |
| 11 | Bingham | 37.1 | Lower | 23.4% | 53 | 22.2% | 0.6*% | 5.4% |
| 12 | Elmore | 34.6 | Lower | 13.0% | 52 | 30.0% | 0.6*% | 6.0% |
| 13 | Nez Perce | 29.4 | Lower | 17.7% | 55 | 26.7% | 0.6*% | 2.6% |
| 14 | Ada | 13.5 | Lower | 17.5% | 44 | 24.1% | 0.3% | 3.1% |
What we will watch
We plan to update this index quarterly, beginning with the first quarter of 2027. Three things will tell us where Idaho goes from here. The first is whether filings keep growing faster than the national pace. In October 2025, lenders filed to foreclose on 206 Idaho properties, 94 percent more than in October 2024, a jump ATTOM’s chief executive said may be an anomaly (Idaho Statesman). The first half of 2026 then brought the 59 percent increase described above. The second is whether the statewide delinquency rate, which rose from 0.4 percent at the end of 2023 to 0.6 percent at the end of 2025, keeps rising. The third is whether Canyon County’s published delinquency rate keeps pulling away from Ada County’s next door.
Sources and data
- Foreclosure activity and trend. ATTOM Data Solutions, 2026 Mid-Year U.S. Foreclosure Market Report (published July 16, 2026), U.S. Foreclosure Rates by State, August 2026 (published September 18, 2026), and Zombie Foreclosure Rates by State, Q3 2026 (published September 4, 2026). Used for statewide filing counts, the national rank, the one-year and two-year changes, the zombie share and count, and the counties listed for August filings and third-quarter zombie foreclosures.
- Historical record. RealtyTrac, 2009 Year-End Foreclosure Market Report (via the Financial Crisis Inquiry Commission archive), and the RealtyTrac 2010 and 2011 year-end foreclosure market reports (published January 12, 2011, and January 9, 2012). Used for the 2009 total, rate, and rank, and the 2010 and 2011 rates.
- Housing market softness. Realtor.com Economic Research, county inventory core metrics through September 2026.
- Housing, mortgage status, cost burden, seasonal homes, and unemployment. U.S. Census Bureau, American Community Survey five-year estimates, 2020 to 2024.
- Current unemployment. U.S. Bureau of Labor Statistics, Local Area Unemployment Statistics, the 12 published months from August 2025 through August 2026 (BLS published no October 2025 figures). Used for the sensitivity test and the current-rate comparisons.
- Mortgage delinquency. CFPB Mortgage Performance Trends, state and county data through December 2025. Used for the 90-or-more day delinquency rates and the national comparison.
- Local context. Idaho Statesman, Foreclosures are rising in Idaho. What’s it mean for homeowners? (November 28, 2025), and its report on 2025 layoffs reported to the state (January 21, 2026).
- Foreclosure process. Idaho Code § 45-1503, § 45-1505, § 45-1506, § 45-1506C, § 45-1508, § 45-1512, § 6-101, and § 11-402. Help resources from HUD, Idaho Legal Aid Services, the Idaho Attorney General, and Idaho Housing and Finance Association.
About NestCash
NestCash buys houses for cash in twelve states and publishes original housing and distressed-property research across U.S. markets. Our original housing research helps homeowners, buyers, and investors understand local market conditions. This report may be cited and its charts embedded with attribution to NestCash.
John is the Founder of NestCash and a leading voice in real estate investing and housing market strategy. With experience across 12 states, he helps buyers, sellers, and investors make smarter decisions using real-world insight and market data.
You're on the list.
We'll email you when the next report is out. One optional question so we can send the right research: