The 2026 Minnesota Foreclosure Risk Index
Where financial pressure on Minnesota homeowners is building, county by county
 Published on October 16th, 2026, by John Carter | Founder, NestCash
Original NestCash research, free to read and cite.
Abstract
Minnesota still has a below-average foreclosure rate, but its filings are rising twice as fast as the nation’s. In the first half of 2026, 3,145 Minnesota properties had a foreclosure filing, one for every 809 housing units, the 27th-highest rate of any state and below the national rate of one in 632. That was 43 percent more than in the first half of 2025, against a national increase of 21 percent (ATTOM Data Solutions). An earlier warning sign is rising too. Pre-foreclosure notices, tracked statewide by the Minnesota Homeownership Center, reached 18,616 in 2025, up 28 percent from the year before and the highest level since 2015. Mortgage delinquency remains low: at the end of 2025, 0.6 percent of Minnesota mortgages were 90 or more days delinquent, against 0.9 percent nationally, up from 0.4 percent two years earlier (Consumer Financial Protection Bureau).
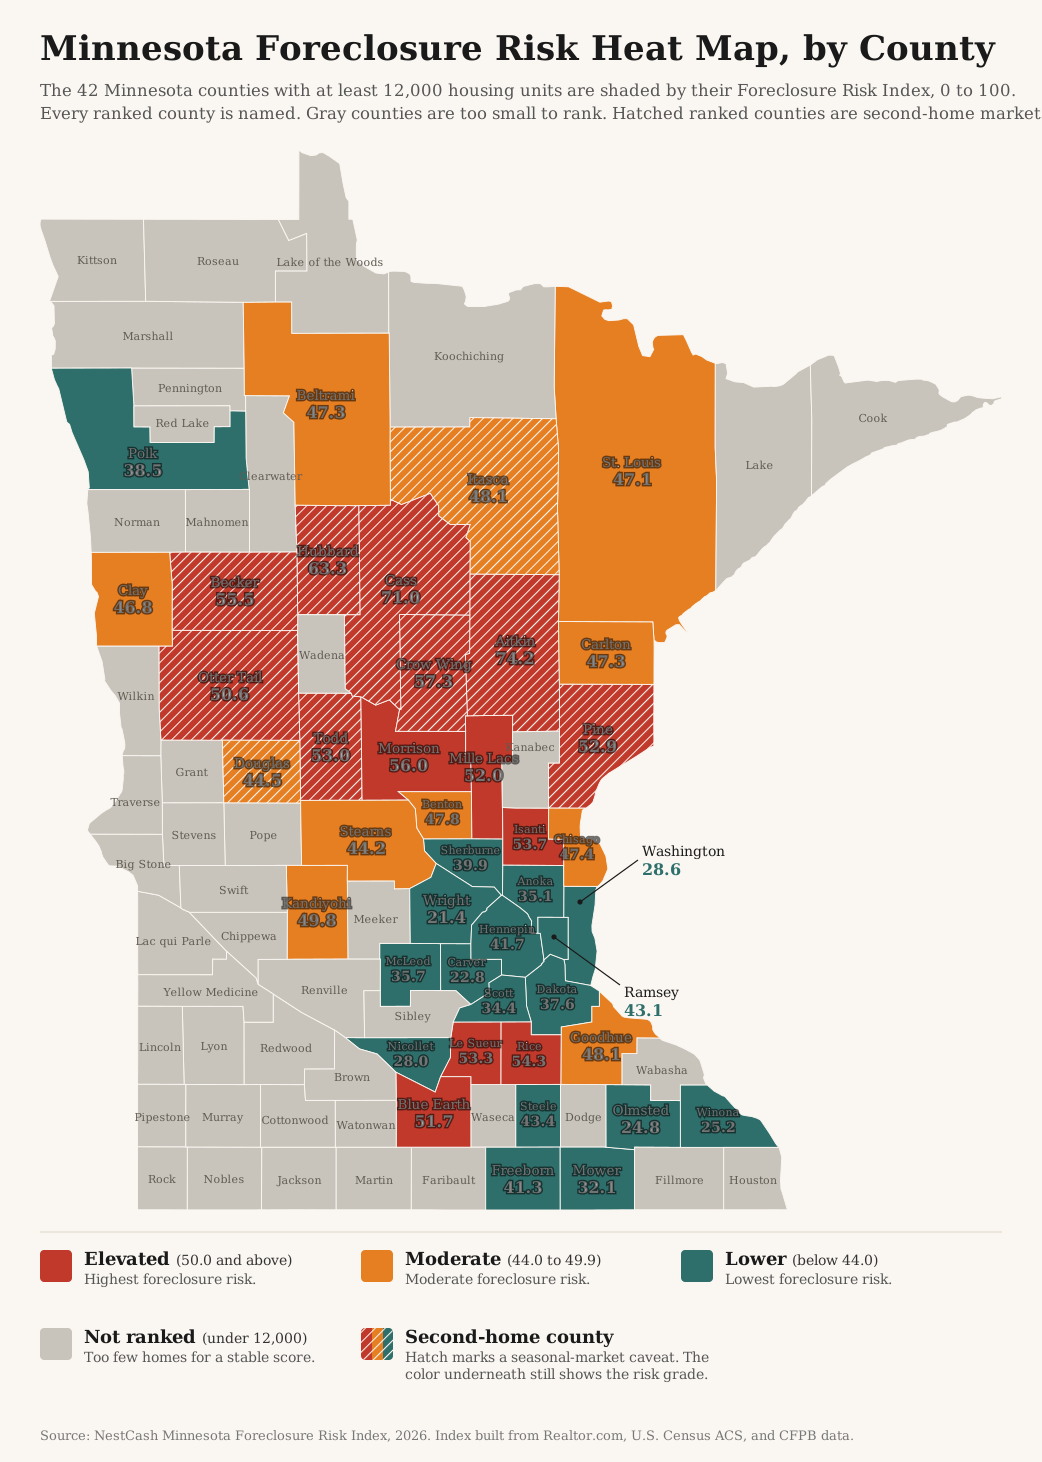
We built a county-level Foreclosure Risk Index from four public datasets to see where the pressure is building. It is concentrated in the lake country of north-central Minnesota. Aitkin County ranks first at 74.2 and is first in every version of the index we tested, followed by Cass, Hubbard, and Crow Wing. These are second-home markets, and we flag them throughout the report. But the pattern is not only seasonal. Morrison County, home to Little Falls, and Isanti County, home to Cambridge, are year-round housing markets that grade Elevated in every version of the index. The Twin Cities grade Lower: Ramsey County ranks 27th and Hennepin County 28th, though both rise when the market is measured by price cuts alone. Wright County ranks last at 21.4.
We score each county from 0 to 100 by blending four public signals, each weighted by how directly it bears on a mortgaged homeowner: market softness (35 percent), mortgage cost burden (30 percent), 90-day mortgage delinquency (20 percent), and unemployment (15 percent). Each signal is min-max normalized within Minnesota, so the score ranks counties against one another in the state, not against a national or absolute standard. A county grades Elevated at 50 or above, Moderate from 44 to 49.9, and Lower below 44. One rule keeps the ranking honest: we rank the 42 counties with at least 12,000 housing units. The other 45 of Minnesota’s 87 counties have too few homes for sale to score a market reliably, so they stay in the data but are not ranked. The 42 ranked counties hold 89.5 percent of the state’s homes. Because several of the top-ranked counties are second-home markets, we flag them, and we tested the index five different ways and report which findings hold in all of them. The full weighting, the normalization, and the limits of the data are spelled out in the methodology section below.
Key findings
- Minnesota’s filings are below average but rising fast. It ranked 27th by foreclosure rate in the first half of 2026, but filings were up 43 percent from a year earlier, twice the national increase of 21 percent (ATTOM Data Solutions). Pre-foreclosure notices reached 18,616 in 2025, the highest level since 2015 (Minnesota Homeownership Center).
- Lake country leads the index. Aitkin County ranks first at 74.2 and is first in all five versions of the index. In Aitkin, 33.6 percent of homeowners with a mortgage spend 30 percent or more of their income on housing, the highest share of any Minnesota county, and Cass County has the second highest, 30.1 percent. Aitkin, Cass, Crow Wing, and Becker grade Elevated in every version. All four are second-home markets, where 25 to 48 percent of homes are held for seasonal use.
- Morrison and Isanti are the year-round story. Morrison County (56.0), home to Little Falls, and Isanti County (53.7), home to Cambridge, are not second-home markets and grade Elevated in all five versions. In August 2026, ATTOM listed Isanti, Mille Lacs, and Le Sueur, all Elevated on our index, among the four Minnesota counties in its monthly report on foreclosure rates.
- The Twin Cities grade Lower, but not firmly. Ramsey County (43.1) and Hennepin County (41.7) rank 27th and 28th. Both grade Elevated when market softness is measured by price cuts alone, and pre-foreclosure notices in the seven-county metro area rose nearly 50 percent from 2024 to 2025, KARE 11 reported.
- Rochester and the western suburbs score lowest among ranked counties. Wright County is last at 21.4, with Carver at 22.8 and Olmsted, home to Rochester, at 24.8. Wright and Olmsted have the lowest published delinquency rate in Minnesota, 0.2 percent. All three grade Lower in every version.
Methodology
Three limits to read first
We state these before the method because they shape how the Minnesota results should be read.
Second-home counties near the top. Median days on market is half of the market-softness input, and in second-home markets it is likely inflated by vacation homes that sit longer on the market. Statewide, 4.9 percent of Minnesota’s homes are held for seasonal, recreational, or occasional use, and the 5 percent cutoff we have used in several states would flag 37 of Minnesota’s 87 counties. As in our New York and Missouri indexes, we instead flag counties at three times the statewide share, 14.8 percent. Ten ranked counties clear that line: Aitkin (47.5 percent), Cass (45.3), Hubbard (37.5), Crow Wing (28.7), Otter Tail (27.5), Pine (25.2), Becker (24.6), Itasca (23.4), Douglas (17.7), and Todd (16.3). Mille Lacs County, at 12.0 percent, is the next ranked county below the line. Eight of the 14 Elevated counties are on the list. Aitkin, Cass, Crow Wing, and Becker stay Elevated in every version of the index, so their scores do not rest on days on market alone. Hubbard, Pine, Todd, and Otter Tail fall to Moderate or Lower when market softness is measured by price cuts alone.
Delinquency data for 12 of 42 ranked counties. The CFPB publishes a county’s 90-day delinquency rate only when the county has enough mortgages in its sample. In Minnesota, 12 ranked counties qualify, 12 of the state’s 13 largest by number of homes. The other 30, including every county in the top 14, carry the statewide rate of 0.6 percent. Their scores rest on market softness, cost burden, and unemployment, not on a measured delinquency rate.
Most counties are too small to rank. Minnesota has 87 counties, and 45 of them have fewer than 12,000 housing units, including most counties in the west and south of the state. Red Lake County, one of the four counties ATTOM listed for Minnesota in its August 2026 filing report, is among them. Our ranked counties cover 89.5 percent of the state’s homes, but the index cannot speak to the smallest rural counties.
We kept the standard formula anyway. Changing the method state by state would break the comparability that makes the series useful, and disclosing where the result is fragile is more useful to readers than tuning it away.
Data and sources
We built the index entirely from public and openly licensed data, and we cite each source at the point of use. Market conditions come from Realtor.com Economic Research (county listing data through September 2026). Housing tenure, mortgage status, cost burden, seasonal homes, county housing counts, and unemployment come from the U.S. Census Bureau’s American Community Survey five-year estimates (2020 to 2024). Mortgage delinquency comes from the Consumer Financial Protection Bureau’s Mortgage Performance Trends (latest data December 2025). Current county unemployment for the sensitivity test comes from the Bureau of Labor Statistics’ Local Area Unemployment Statistics. Statewide filing counts, national ranks, and trends come from ATTOM Data Solutions’ published foreclosure market reports, and Minnesota’s sheriff’s-sale and pre-foreclosure-notice counts from the Minnesota Homeownership Center. Every dataset we used is free and publicly available.
Building the index
The Minnesota Foreclosure Risk Index uses the same formula as every state in this series, a weighted blend of four signals, each chosen because it precedes or predicts foreclosure among homeowners who carry a mortgage:
35%
The share of active listings with a price cut and the median days a home sits on the market. A soft market matters because a homeowner in trouble who cannot sell quickly has fewer ways to avoid foreclosure. See the note on second-home counties above.
30%
The share of owners with a mortgage who spend 30 percent or more of household income on housing. This is direct payment stress on the exact population that can be foreclosed on.
20%
The 90-day-or-more delinquency rate, the clearest early warning that foreclosures are coming. Published for 12 of Minnesota’s 42 ranked counties. See the note above.
15%
A secondary driver. We hold its weight down deliberately, because unemployment also captures renters and therefore dilutes a signal meant to describe homeowners.
We normalized each signal across the 42 ranked counties on a 0-to-1 scale, where 0 is the lowest value in that set and 1 is the highest, then applied the weights above and multiplied by 100. The result is a relative score: it ranks Minnesota counties against one another, not against a national or absolute standard. We then graded each county by its score, Elevated for 50.0 or above, Moderate for 44.0 to 49.9, and Lower for anything below 44.0. Fourteen counties land in the Elevated tier, 11 in Moderate, and 17 in Lower. The 14 Elevated counties hold 11.7 percent of the state’s homes, because none of the large metro counties is among them.
To test how much the results depend on any one input, we scored the counties five ways: the standard index; the standard index with current Bureau of Labor Statistics unemployment, the 12 published months from August 2025 through August 2026, in place of the Census five-year estimate; the index with delinquency removed and its weight spread proportionally across the other three signals; the index with market softness measured by price cuts alone; and price cuts alone combined with current BLS unemployment. When we call a finding robust in this report, it holds in all five.
Other limitations
The index is relative. A Lower grade means lower measured risk than other Minnesota counties, not low risk in absolute terms. It also measures leading pressure, not completed foreclosures or filings, so it will not match any single month’s filing counts. The Census five-year unemployment estimate runs below current BLS unemployment in several of the top counties, including Morrison (4.0 percent against 6.4), Mille Lacs (4.0 against 6.7), and Pine (5.6 against 7.8), and the BLS test shows how the ranking moves with current data. Parts of the Leech Lake and Mille Lacs reservations lie within ranked counties, and the county-level data we use do not separate tribal land. Counties that tie at the published one-decimal score share a rank.
Findings
The index
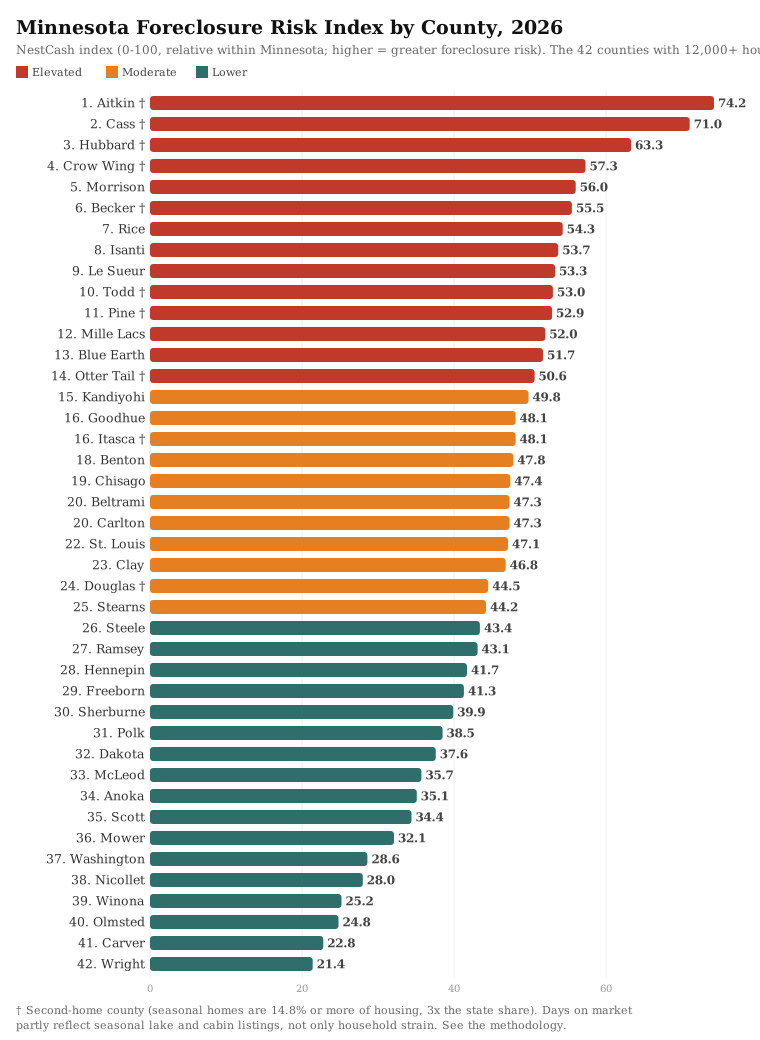
Ranked from most to least risk on the standard formula. Read the daggered second-home counties with the limits above in mind.
Lake country
The four highest scores of any ranked county belong to the lake counties of north-central Minnesota, around Brainerd. Aitkin County scores 74.2 and ranks first in all five versions of the index. Cass (71.0), Hubbard (63.3), and Crow Wing (57.3) follow, with Becker (55.5) sixth. Aitkin, Cass, Crow Wing, and Becker grade Elevated in every version.
These counties carry real pressure on year-round homeowners. In Aitkin, 33.6 percent of homeowners with a mortgage spend 30 percent or more of their income on housing, the highest share of any Minnesota county, and in Cass 30.1 percent, the second highest. Cass has the highest five-year unemployment estimate of any ranked county, 6.6 percent, and Aitkin’s current 12-month rate, 7.3 percent, is the second highest of any ranked county, behind Pine at 7.8. But these are also among the most seasonal housing markets in the state, where 25 to 48 percent of homes are held for seasonal use, and none of them has a published delinquency rate. Listings in Hubbard County have been on the market a median of 81 days, the longest of any ranked county. Hubbard shows how much the seasonal market can move a rank: it falls from third to 20th, and from Elevated to Moderate, when market softness is measured by price cuts alone. Otter Tail County, 14th on the standard index, falls to 33rd on the same test.
Morrison, Isanti, and the year-round counties
Morrison County, home to Little Falls, ranks fifth at 56.0. It is the highest-ranked county that is not a second-home market, with 9.7 percent of its homes held for seasonal use, and it grades Elevated in all five versions of the index, ranking as high as third. 29.8 percent of its homeowners with a mortgage spend 30 percent or more of their income on housing, the third-highest share of any ranked county, and its current unemployment rate is 6.4 percent, well above its five-year estimate. In January 2026, Wabash National announced it would permanently close its Little Falls plant on April 17, with the layoff of all 56 employees (KNSI).
Isanti County, home to Cambridge, ranks eighth at 53.7 and also grades Elevated in all five versions, rising to third when market softness is measured by price cuts alone and to second when price cuts are combined with current unemployment. Its listings spend less time on the market than those in most ranked counties, a median of 39 days, but 24.8 percent of its listings carry a price cut and 29.3 percent of its homeowners with a mortgage spend 30 percent or more of their income on housing. Rice County (54.3), home to Faribault, Le Sueur (53.3), Mille Lacs (52.0), and Blue Earth (51.7), home to Mankato, also grade Elevated on the standard index, though less firmly. Le Sueur has the second-highest share of listings with a price cut of any ranked county, 27.3 percent. Mille Lacs falls to Moderate when delinquency is removed, and Blue Earth falls to Lower with current unemployment.
In August 2026, ATTOM listed four Minnesota counties in its monthly report on foreclosure rates by state: Red Lake, Mille Lacs, Isanti, and Le Sueur. Red Lake is too small to rank. The other three all grade Elevated on our index.
The Twin Cities
Minnesota’s two largest counties grade Lower. Ramsey County, home to St. Paul, scores 43.1 and ranks 27th, and Hennepin County, home to Minneapolis and the largest county in the state with 571,527 homes, scores 41.7 and ranks 28th. Both have measured delinquency rates at or below the statewide rate, 0.4 percent in Ramsey and 0.6 percent in Hennepin. But neither grade is firm. When market softness is measured by price cuts alone, Ramsey rises to 10th and Hennepin to 18th, and both grade Elevated. Their listings spend little time on the market, a median of 38 days in Ramsey and 42 in Hennepin, which holds down their standard scores, but 25.1 percent of Ramsey’s listings and 23.5 percent of Hennepin’s carry a price cut. Pre-foreclosure notices in the seven-county metro area rose nearly 50 percent from 2024 to 2025, KARE 11 reported. Separately, in the third quarter of 2026, ATTOM’s Minnesota entry on zombie foreclosures, homes left vacant during the foreclosure process, listed St. Louis, Hennepin, Ramsey, and Anoka counties. The state had only 54 such properties.
The Twin Cities suburbs score lower still. Dakota (37.6), Anoka (35.1), Scott (34.4), Washington (28.6), and Carver (22.8) all grade Lower, and Scott, Washington, and Carver grade Lower in every version.
Rochester and the lowest-risk counties
The lowest scores of any ranked county belong to Wright County, home to Buffalo, last at 21.4, Carver County at 22.8, and Olmsted County, home to Rochester and the Mayo Clinic, at 24.8. Wright and Olmsted have the lowest published delinquency rate in the state, 0.2 percent. Winona (25.2) and Nicollet (28.0) follow. Wright ranks last on the standard index, and Olmsted ranks last in three of the other four versions. All five grade Lower in every version.
How today compares with the last crisis
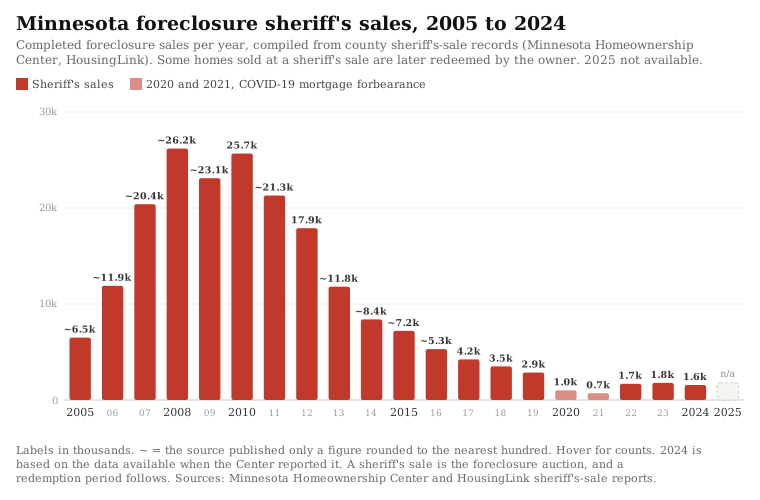
Minnesota has its own count of completed foreclosure sales, compiled from county sheriff’s-sale records by the Minnesota Homeownership Center and, for earlier years, HousingLink. A sheriff’s sale is the foreclosure auction, and some owners later redeem their homes during the redemption period that follows. By that measure, sheriff’s sales reached the highest level in the series in 2008, about 26,200, and stayed above 20,000 a year through 2011 (Minnesota Homeownership Center and HousingLink). Sales then fell every year to 712 in 2021, and the Center notes that its 2020 and 2021 figures reflect COVID-19 mortgage forbearance. Sales rose to 1,692 in 2022 and 1,781 in 2023. The Center counted 1,563 in 2024, based on the data available when it reported, about 6 percent of the 2008 total. We found no published count for 2025.
The earlier warning signs are rising faster. Pre-foreclosure notices, which the Center also tracks, reached 18,616 in 2025, up 28 percent from 2024 and the highest level since 2015. That is still far below the more than 71,000 notices Minnesota homeowners received at the height of the crisis in 2010 (Minnesota Homeownership Center). A notice is a warning, not a foreclosure: in 2023, there were about six notices for every sheriff’s sale.
If you are a Minnesota homeowner facing foreclosure
This report is a market analysis, not legal advice, but the data points to a few things worth knowing. Minnesota allows foreclosure by court action (Minn. Stat. ch. 581) or, most often, by advertisement, outside of court (Minn. Stat. ch. 580). In a foreclosure by advertisement, notice of the sale must be published for six weeks, and a copy of the notice must be served on the occupant at least four weeks before the sale (580.03). The sheriff sells the home at public auction in the county where it is located (580.06).
Before a foreclosure starts, the party foreclosing must tell an owner-occupant that foreclosure prevention counseling is available and that it will send the owner’s name, address, and phone number to an approved counseling agency, which it must then do (580.021). After the sheriff’s sale, you generally have six months to redeem the home by paying the amount it sold for, plus interest and costs. The period is 12 months in some cases, including when less than two-thirds of the original loan is still owed or the home has a reverse mortgage (580.23). It can be cut to five weeks if a court finds the home abandoned (582.032), or if you choose to postpone the sale to gain time to catch up (580.07).
Unpaid property taxes are a separate process. In 2023, in Tyler v. Hennepin County, the U.S. Supreme Court held that a Minneapolis homeowner plausibly alleged that the county violated the Constitution by keeping the value of her condominium above her tax debt. In 2024, Minnesota changed its tax-forfeiture law so that former owners may be entitled to proceeds from a later sale (Minnesota House).
Help is available, and it is free. The Minnesota Homeownership Center connects homeowners with foreclosure prevention advisors across the state at 651-659-9336 or, toll free, 866-462-6466 (Minnesota Homeownership Center). A HUD-approved housing counselor can also review your options: call (800) 569-4287 to find one near you (HUD). For legal help, you can call your legal aid office at 1-877-696-6529 (LawHelpMN). The state’s HomeHelpMN program, which used federal Homeowner Assistance Fund money, stopped taking applications on July 7, 2023 (Minnesota Housing). Be wary of anyone who charges up-front fees to stop a foreclosure or asks you to sign over the deed to your home. Minnesota’s required foreclosure notice warns that after a sale, people may approach you to buy or transfer your house for little or no money (580.041).
The full data
All 42 ranked counties, from highest to lowest Foreclosure Risk Index. An asterisk on the delinquency rate marks a county where the Minnesota statewide rate was substituted because its own rate is not separately reported. A dagger marks a second-home county, where seasonal homes are 14.8 percent or more of housing. Unemployment is the five-year Census estimate used in the index. Counties that tie at the published score share a rank.
| Rank | County | FRI | Grade | Price cuts | Median DOM | Cost burden | 90+ delinq | Unemployment |
|---|---|---|---|---|---|---|---|---|
| 1 | Aitkin † | 74.2 | Elevated | 21.8% | 62 | 33.6% | 0.6*% | 5.8% |
| 2 | Cass † | 71.0 | Elevated | 20.2% | 69 | 30.1% | 0.6*% | 6.6% |
| 3 | Hubbard † | 63.3 | Elevated | 16.8% | 81 | 29.4% | 0.6*% | 4.4% |
| 4 | Crow Wing † | 57.3 | Elevated | 20.5% | 56 | 27.6% | 0.6*% | 5.5% |
| 5 | Morrison | 56.0 | Elevated | 21.5% | 52 | 29.8% | 0.6*% | 4.0% |
| 6 | Becker † | 55.5 | Elevated | 21.3% | 62 | 27.1% | 0.6*% | 4.3% |
| 7 | Rice | 54.3 | Elevated | 19.9% | 50 | 29.2% | 0.6*% | 4.6% |
| 8 | Isanti | 53.7 | Elevated | 24.8% | 39 | 29.3% | 0.6*% | 4.1% |
| 9 | Le Sueur | 53.3 | Elevated | 27.3% | 57 | 23.9% | 0.6*% | 4.2% |
| 10 | Todd † | 53.0 | Elevated | 19.1% | 60 | 27.8% | 0.6*% | 4.1% |
| 11 | Pine † | 52.9 | Elevated | 16.7% | 58 | 26.9% | 0.6*% | 5.6% |
| 12 | Mille Lacs | 52.0 | Elevated | 21.5% | 52 | 27.8% | 0.6*% | 4.0% |
| 13 | Blue Earth | 51.7 | Elevated | 24.4% | 59 | 23.1% | 0.6*% | 4.9% |
| 14 | Otter Tail † | 50.6 | Elevated | 15.1% | 77 | 24.1% | 0.6*% | 4.8% |
| 15 | Kandiyohi | 49.8 | Moderate | 25.1% | 57 | 24.4% | 0.6*% | 3.6% |
| 16 | Goodhue | 48.1 | Moderate | 17.4% | 68 | 25.5% | 0.6*% | 3.6% |
| 16 | Itasca † | 48.1 | Moderate | 15.2% | 55 | 25.4% | 0.6*% | 5.9% |
| 18 | Benton | 47.8 | Moderate | 26.2% | 49 | 23.9% | 0.6*% | 3.9% |
| 19 | Chisago | 47.4 | Moderate | 21.2% | 50 | 25.9% | 0.6*% | 4.1% |
| 20 | Beltrami | 47.3 | Moderate | 15.3% | 60 | 26.0% | 0.6*% | 4.7% |
| 20 | Carlton | 47.3 | Moderate | 14.1% | 80 | 22.4% | 0.6*% | 4.8% |
| 22 | St. Louis | 47.1 | Moderate | 19.9% | 57 | 22.5% | 0.7% | 4.6% |
| 23 | Clay | 46.8 | Moderate | 29.8% | 54 | 20.1% | 0.6*% | 4.1% |
| 24 | Douglas † | 44.5 | Moderate | 20.7% | 56 | 25.5% | 0.6*% | 2.9% |
| 25 | Stearns | 44.2 | Moderate | 23.8% | 48 | 21.6% | 0.7% | 4.1% |
| 26 | Steele | 43.4 | Lower | 26.7% | 51 | 21.9% | 0.6*% | 3.4% |
| 27 | Ramsey | 43.1 | Lower | 25.1% | 38 | 26.0% | 0.4% | 4.9% |
| 28 | Hennepin | 41.7 | Lower | 23.5% | 42 | 22.7% | 0.6% | 4.5% |
| 29 | Freeborn | 41.3 | Lower | 13.7% | 67 | 22.6% | 0.6*% | 4.6% |
| 30 | Sherburne | 39.9 | Lower | 21.0% | 43 | 22.2% | 0.8% | 3.0% |
| 31 | Polk | 38.5 | Lower | 16.8% | 65 | 21.6% | 0.6*% | 3.6% |
| 32 | Dakota | 37.6 | Lower | 23.2% | 40 | 21.1% | 0.7% | 3.6% |
| 33 | McLeod | 35.7 | Lower | 19.6% | 42 | 23.9% | 0.6*% | 3.3% |
| 34 | Anoka | 35.1 | Lower | 22.3% | 39 | 22.7% | 0.5% | 4.3% |
| 35 | Scott | 34.4 | Lower | 19.0% | 46 | 22.4% | 0.6% | 3.5% |
| 36 | Mower | 32.1 | Lower | 16.4% | 43 | 22.6% | 0.6*% | 3.9% |
| 37 | Washington | 28.6 | Lower | 23.3% | 38 | 22.3% | 0.4% | 3.4% |
| 38 | Nicollet | 28.0 | Lower | 22.7% | 50 | 18.6% | 0.6*% | 2.2% |
| 39 | Winona | 25.2 | Lower | 18.6% | 43 | 20.7% | 0.6*% | 2.3% |
| 40 | Olmsted | 24.8 | Lower | 23.7% | 60 | 18.7% | 0.2% | 3.6% |
| 41 | Carver | 22.8 | Lower | 20.0% | 41 | 21.1% | 0.4% | 3.1% |
| 42 | Wright | 21.4 | Lower | 21.1% | 42 | 23.6% | 0.2% | 2.7% |
Forty-five counties are not ranked because they fall below the 12,000-housing-unit floor: Big Stone, Brown, Chippewa, Clearwater, Cook, Cottonwood, Dodge, Faribault, Fillmore, Grant, Houston, Jackson, Kanabec, Kittson, Koochiching, Lac qui Parle, Lake, Lake of the Woods, Lincoln, Lyon, Mahnomen, Marshall, Martin, Meeker, Murray, Nobles, Norman, Pennington, Pipestone, Pope, Red Lake, Redwood, Renville, Rock, Roseau, Sibley, Stevens, Swift, Traverse, Wabasha, Wadena, Waseca, Watonwan, Wilkin, and Yellow Medicine.
What we will watch
We plan to update this index quarterly, beginning with the first quarter of 2027. Three things will tell us where Minnesota goes from here: whether the surge in pre-foreclosure notices turns into more sheriff’s sales, which stayed under 2,000 a year from 2020 through 2024; whether filings keep rising faster than the national rate; and whether Hennepin and Ramsey, which grade Lower on the standard index but Elevated on price cuts, move up as the metro’s rise in pre-foreclosure notices works through.
Sources and data
- Foreclosure activity and trend. ATTOM Data Solutions, 2026 Mid-Year U.S. Foreclosure Market Report (published July 16, 2026), U.S. Foreclosure Rates by State, August 2026 (published September 18, 2026), and Zombie Foreclosure Rates by State, Q3 2026 (published September 4, 2026). Used for statewide filing counts, the national rank, the year-over-year change, and the counties listed for August filings and third-quarter zombie foreclosures.
- Historical record and pre-foreclosure notices. Minnesota Homeownership Center, 2018 Annual Foreclosures in Minnesota, HousingLink, 2012 Foreclosures in Minnesota, and the Center’s 2019 to 2024 community impact reports and October 2026 update. Used for the annual sheriff’s-sale counts and pre-foreclosure notices. KARE 11, Data shows increase in Minnesota homeowners at risk of foreclosure, for the Twin Cities metro change.
- Housing market softness. Realtor.com Economic Research, county inventory core metrics through September 2026.
- Housing, mortgage status, cost burden, seasonal homes, and unemployment. U.S. Census Bureau, American Community Survey five-year estimates, 2020 to 2024.
- Current unemployment. U.S. Bureau of Labor Statistics, Local Area Unemployment Statistics, the 12 published months from August 2025 through August 2026 (BLS published no October 2025 figures). Used for the sensitivity test and the current-rate comparisons.
- Mortgage delinquency. CFPB Mortgage Performance Trends, state and county data through December 2025. Used for the 90-or-more day delinquency rates and the national comparison.
- Local context. KNSI on the Wabash National closure in Little Falls, and the Minnesota Indian Affairs Council on the Leech Lake and Mille Lacs reservations.
- Foreclosure process. Minnesota Statutes sections 580.021, 580.03, 580.041, 580.06, 580.07, 580.23, 581.10, and 582.032, Tyler v. Hennepin County (2023), and the Minnesota House summary of 2024 laws. Help resources from the Minnesota Homeownership Center, HUD, LawHelpMN, and Minnesota Housing.
About NestCash
NestCash buys houses for cash in twelve states and publishes original housing and distressed-property research across U.S. markets. Our original housing research helps homeowners, buyers, and investors understand local market conditions. This report may be cited and its charts embedded with attribution to NestCash.
John is the Founder of NestCash and a leading voice in real estate investing and housing market strategy. With experience across 12 states, he helps buyers, sellers, and investors make smarter decisions using real-world insight and market data.